In this guide 6 sections
A ledger schedule is enough while you own a few dozen assets, use one depreciation method and rarely dispose of anything. Move to a register when you need tags, locations, insurance and service dates, or depreciation per asset. It then serves audits and maintenance, not just the books.
What the ledger gives you and what it hides
The general ledger holds a balance per asset class: plant and machinery, vehicles, computers, furniture. Each class shows cost, depreciation and net value. For many small firms that is all the auditor asks to see, and it is enough.
The ledger cannot tell you which lathe stands in which shed. It cannot say that the delivery van bought in March is the one that failed its fitness test last week. A balance is a total. It is not a list of things.
That gap is harmless when you can walk the premises and name every item. It turns costly with several sites, many small items, or staff who move equipment between rooms and branches without telling accounts a word.
Count the assets and the places
Start with numbers. How many items sit above your capitalisation limit, and how many sites hold them? A single office with thirty items can live happily on a spreadsheet schedule kept by one careful person.
Two hundred laptops, handsets, forklifts and test benches across five sites cannot. Someone leaves. A laptop goes home. Nobody knows whose it is, and verification at year end means walking every floor of every site with a printout.
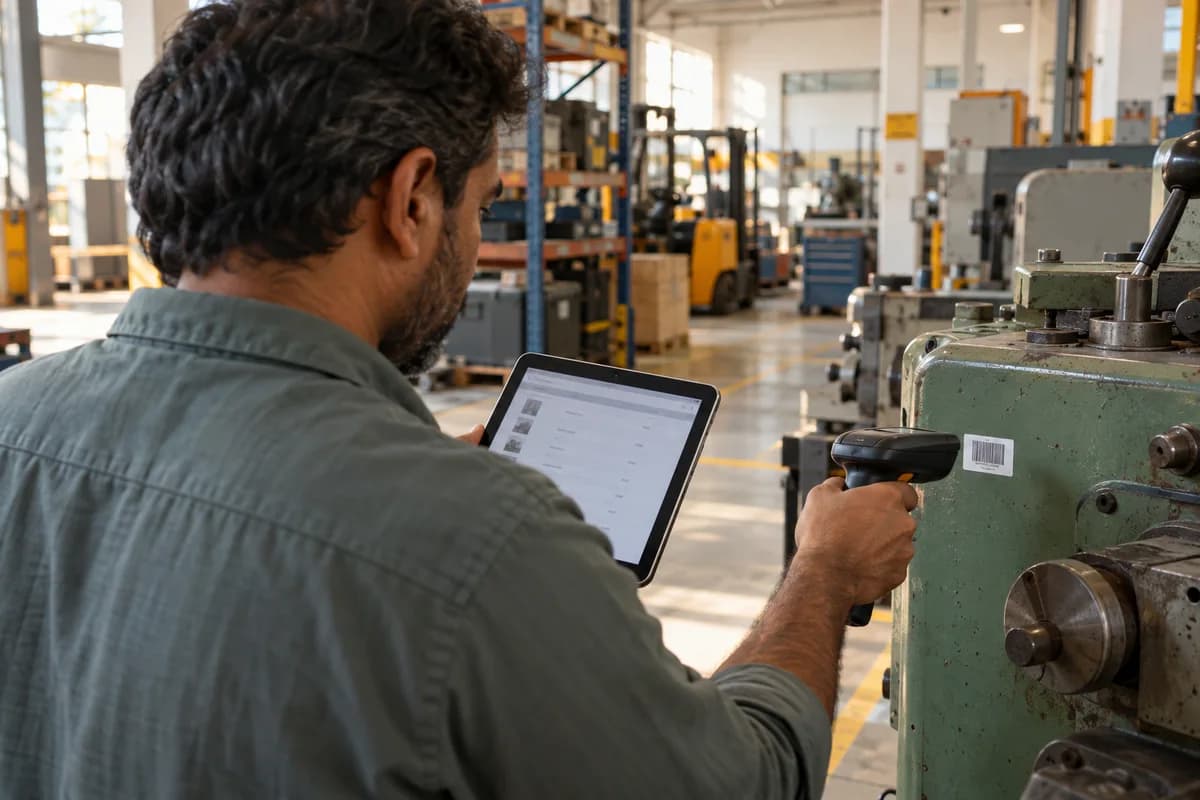
A register gives each asset a tag number, a location, a custodian and a photograph. The yearly count becomes a scan with a handheld device or a phone, and the differences list themselves. No printouts.
- Number of assets above the capitalisation limit
- Number of sites and rooms
- Items that move between people
- Items bought in lots, such as fifty chairs
Check depreciation, insurance and disposals
Depreciation is where ledger schedules strain. One class may use straight line for the books and a reducing balance method for tax. The schedule then needs two sets of columns per asset, rebuilt every year by hand, and mistakes creep in.
Insurance is the second test. A policy lists insured items with values and renewal dates. If your fleet or machinery changes during the year, the policy and the books drift apart. A claim then exposes the gap at the worst possible moment.
Disposals are the third. A sale, scrapping or write-off must remove cost and accumulated depreciation, work out the gain or loss on that item. Keep the approval and the buyer’s paper with it. A register does this per asset and leaves a trail.
- Different methods for books and tax
- Component assets with separate lives
- Insurance values and renewal dates
- Sale, scrap and write-off entries with approval
Tie the register to service contracts
The strongest reason for a register is not accounting. It is maintenance. Each machine has an annual maintenance contract, a warranty end date, a service history and a vendor who must be called when something breaks.
If the register holds those dates, the maintenance team gets next month’s renewals as a list. A lapsed contract on a chiller or a CNC machine is often found only when the machine stops. By then the repair is billed at full price.
Where assets are few and service is informal, skip this. Where an idle day costs real output and a delayed shipment, keep the register linked to contract tracking so that every renewal date reaches a person.
A simple rule of thumb
Stay with the ledger if you hold under fifty assets on one site, with one depreciation method and no contracts to track. Keep a spreadsheet of serial numbers beside it. That is plenty.
Move to a register when any two of these are true. You run several sites. Book and tax depreciation differ. An insurance claim has been disputed. An auditor has asked for a tag-wise list. One alone is a warning.
This week, count the assets above your limit and compare the number with the ledger schedule. Can you finish in an afternoon? If not, you have your answer.
Asset register readiness worksheet
This worksheet runs to one page in three parts. Part one counts assets, sites and the capitalisation limit. Part two ticks the depreciation methods, insurance policies and service contracts in use. Part three scores each answer and ends with a result line that reads ledger schedule, spreadsheet register or full register, so the reader leaves with a decision.
Open a blank worksheet to printQuestions owners ask
Is a fixed asset register compulsory?
Rules differ by country and company type. Many auditors expect asset-wise records in some form. Ask your accountant what your jurisdiction requires.
Can a spreadsheet work as a register?
For a small number of assets, yes. It breaks when several people edit it, tags drift, or depreciation must run under two methods.
How do I tag existing assets?
Walk each site with a printed list, attach tags in sequence, photograph every item and record location and custodian. Then reconcile the total to the ledger.
What should the register track beyond cost?
Purchase invoice, serial number, custodian, location, insurance, warranty and service dates, and the disposal record when the asset leaves.