In this guide 6 sections
Close in dependency order. Fix branch cutoffs first, then reconcile each bank account, clear inter branch transfers, post accruals, consolidate and lock the period. Every step needs a named signer, because a step built on an unsigned one gets redone. Afterwards, the audit log should show who closed what and when.
Fix the cutoff at every branch before anything else
Every branch must stop posting to the old month together. Choose a time such as noon on day one and tell each branch accountant in writing. Late bills still belong to the month they happened in.
Ask each branch for four numbers: the last invoice, the last goods receipt note, the last cash voucher and the last stock transfer. It takes minutes. It saves days of argument about which month a document belongs to.
A cash receipt dated the 30th but keyed on the 3rd is the classic culprit when five cities disagree, and finding it by hand is miserable. Spot checks help. Pick five random vouchers per branch and confirm their dates match the day they were physically signed.
- Last invoice number per branch
- Last goods receipt note per branch
- Last cash voucher and petty cash slip
- Last stock transfer sent or received
- Name of the person who confirmed the cutoff
Reconcile every bank account against its statement
Reconciliation comes second because it exposes what branches forgot to record: bank charges, standing instructions, returned cheques and customer deposits that have no invoice behind them. Each branch reconciles its own account while head office handles the central ones. Put a name against each account in the checklist. Shared accounts get ignored.
Start from the statement closing balance. List cheques issued but uncleared and deposits in transit, then check the adjusted figures agree. Anything unexplained after two passes goes to the controller with a note.
Old unmatched items need a decision. Write them off, chase them or reverse them, but never carry them forward again without a reason. A cheque outstanding for six months is usually stale, and the issuing branch should say so in writing before head office reverses it.
Clear inter branch transfers before consolidation
A transfer between branches is recorded twice, once as an outflow and once as an inflow. If the receiving branch has not booked its side by the cutoff, the group shows stock that vanished or appeared from nowhere.
Print the inter branch account for each pair and compare balances, which should be equal and opposite. Where they differ, find the goods in transit, book the receipt with a clear note and clear the gap before moving on. Hand delivered goods with a driver’s slip are the usual trouble, since the slip often reaches the branch days after the truck does.
Never force a balance with a journal. That hides the very error this account exists to reveal.
- Transfer note numbers, sent against received
- Goods in transit at the cutoff
- Cash sent to head office but not yet banked
- Shared cost allocations posted by one side only
Post accruals and prepayments, then consolidate
Accruals follow reconciliation because the statement shows which bills were already paid. Book the rent, electricity, freight and wages that belong to the month but have no invoice yet, after reversing last month’s accruals so nothing counts twice.
Spread prepayments such as insurance and annual maintenance contracts over the months they cover. Keep a schedule with start date, end date and monthly amount. It rolls forward easily. Ask the branch for the rent agreement and the insurance schedule once a year. Then the figures stay honest.
Consolidation then adds the branches, eliminates the inter branch balances and produces the group trial balance. Read it before sending it on. A branch with no payroll cost is an error, not a result.
Lock the period and read the audit log
Locking stops anyone posting backdated entries to a closed month. Do it only after the controller signs the checklist. Later corrections go through a dated adjusting entry in the open month, with a reason attached. Exceptions happen. When a correction cannot wait, the controller signs the reopening and the system records it.
Open the audit log and check that it tells a clear story: who ran each reconciliation, who approved each journal, who locked the period and at what time. Edits to old vouchers and changed posting dates deserve a second look.
File the signed checklist, the reconciliations and the consolidation workbook in one folder per month. Next month, copy the checklist from this one and start there. One folder, one month, one owner. That habit makes an external audit far calmer, because the auditor finds every reconciliation where it should be.
- Signer and time for each of the five steps
- Journals posted after the cutoff, with reasons
- Users who changed a posting date
- Period lock date and the person who set it
Month end close tracker
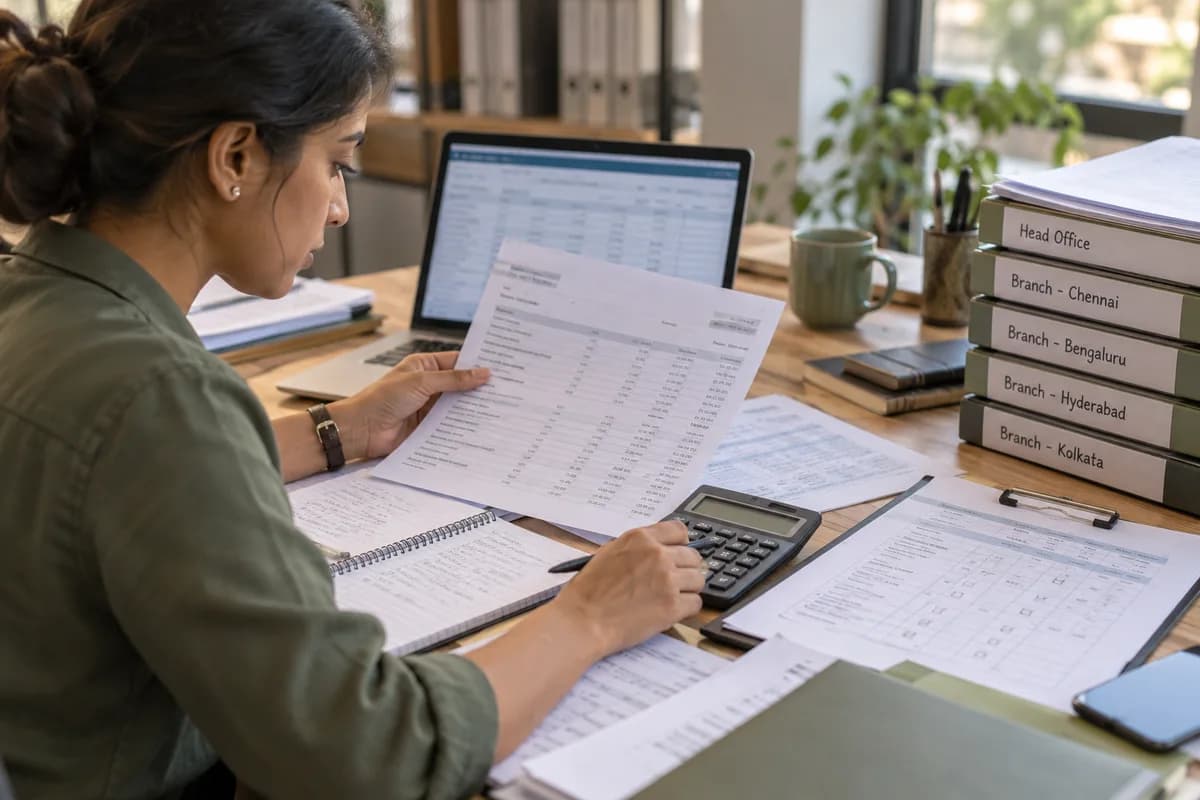
A single page grid with one row per close step and one column per branch. Columns show owner, due date, status, sign off initials and notes. Rows run from cutoff confirmation through bank reconciliation, inter branch matching, accruals, consolidation review and period lock. A final block lists the audit log checks.
Open a blank worksheet to printQuestions owners ask
How many working days should a month end close take?
It depends on the number of branches and how many reconciliations stay open. Record the days this month took, find the slowest step and shorten that first. Speed comes from fewer late corrections.
Who should sign off each step of the close?
Branch accountants sign the cutoff and their own bank reconciliation. The head office accountant signs inter branch matching and accruals. The controller signs consolidation and the lock. Nobody approves their own work.
What if a branch misses the cutoff?
Do not hold the whole group. Estimate the missing branch with an accrual, mark it clearly and replace it with actuals next month. Note the delay on the checklist so the cause gets fixed.
Can software run the close on its own?
It can enforce the order, block posting after a lock date, match transfers and keep the log. People still judge estimates and odd balances. Think of the system as the checklist’s enforcer.