In this guide 6 sections
Most royalty errors come from an unclear sales base, rules applied by hand, ad fund levies mixed into royalty, late fees charged inconsistently and outlet figures nobody can verify. Store each rule against the agreement, calculate royalty from locked daily sales, and send a statement the franchisee can check line by line.
Charging on the wrong sales base
Some agreements charge royalty on gross sales and some on net, and net may exclude discounts, refunds, tax or delivery partner commissions. The contract wording decides. Applying the wrong one is easy.
The common slip is taking whichever figure is easiest to pull from the till report, which often includes tax that no agreement intended to charge royalty on. Check the clause instead.
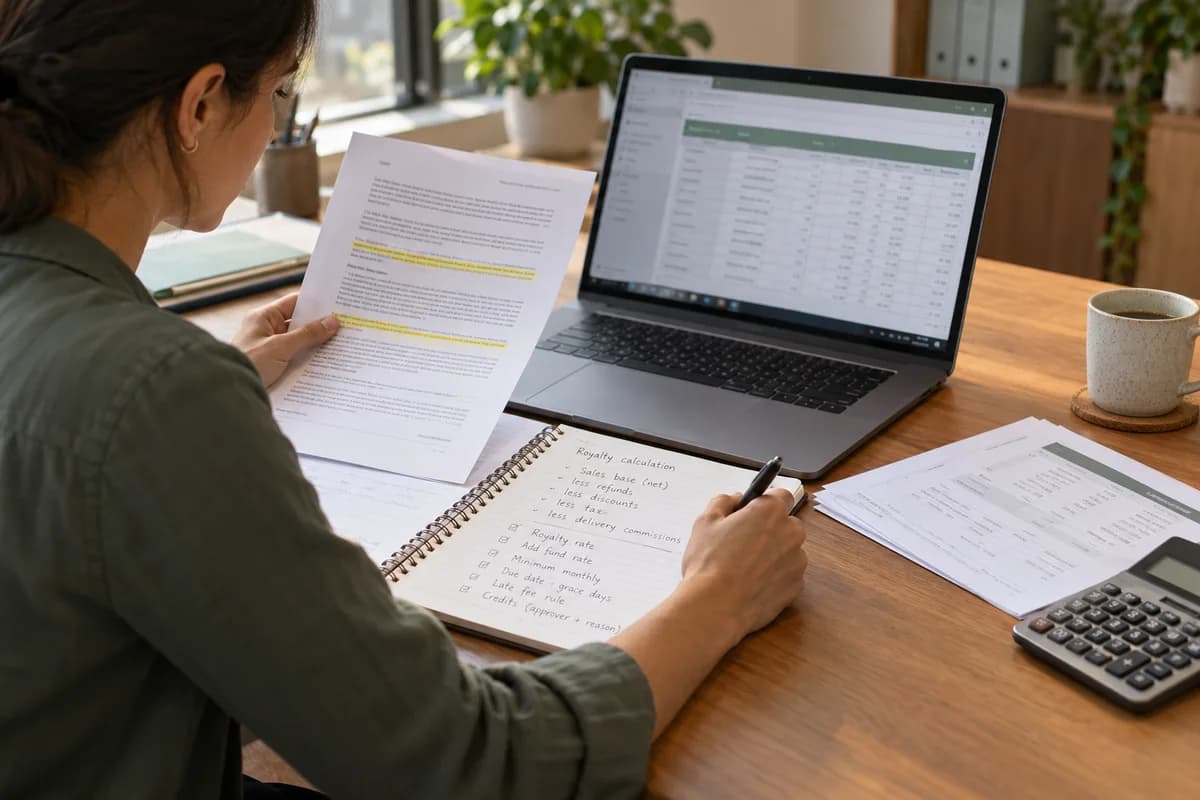
Read the clause, then write the base as a formula that shows which lines are added and which are taken off, such as refunds, discount vouchers and tax. Attach that formula to the outlet record.
- Tax counted inside or outside the base
- Refunds deducted in the month of sale or return
- Discount vouchers funded by head office
- Delivery platform commissions
- Gift card sales versus redemptions
Mixing the ad fund with royalty
Ad fund contributions are a separate levy with their own rate, bank account and sometimes their own base, which is why they belong on their own line. When a statement shows one combined line, nobody can tell whether the marketing fund was collected correctly, or whether the royalty side was undercharged to compensate.
Keep them as two lines. The fund needs its own ledger too, because franchisees will ask what it paid for, and a campaign invoice answers that better than a promise.
Local campaigns add a wrinkle. If an outlet spends its own money on promotion and the agreement credits part of it, record that credit as a line, not a quiet adjustment.
Late fees, credits and rules that differ by outlet
Late fees need three fixed inputs. If finance waives it for a friendly franchisee in March and charges another franchisee in April, the outlet that paid has every reason to feel cheated.
Agreements signed in different years carry different terms. A first-year concession, a minimum monthly royalty and a capped fee all live in different documents, often a signed agreement, a side letter and an email.
Give each term its own field. Waivers then need an approver and a written reason, and the statement prints both beside the credit so the franchisee and the auditor see the same trail.
- Due date and grace days
- Minimum monthly royalty
- First-year reduced rate
- Credit notes with approver and reason
Disputed figures and the missing evidence
An outlet says sales were lower than billed. Without daily submissions you hold only a monthly total and a memory of one phone call, and neither wins against a franchisee holding printed till tapes.
Calculate from locked daily sales instead. Each statement then links back to the days that produced it, and the franchisee can see the exact Saturday they dispute, with the voids and refunds booked that evening.
The till tape wins. Where the outlet’s till total and the reported figure differ, a point of sale integration or an uploaded end-of-day Z-report settles the question without a phone call.
Let the statement do the arguing
An automated statement lists reported sales, adjustments, the base, the rate, the royalty, the ad fund, fees and credits in a fixed order that any franchisee can follow. Every number has a source. Nothing is typed from memory.
Issue it on a fixed date. Franchisees stop calling to ask how a figure was reached, because the answer is on the page, along with the payment terms and the due date.
Pick your three oldest agreements and recompute last quarter by hand against the contract text, including every fee waiver and credit note that finance issued. Each difference is a first fix.
Royalty rule worksheet
One line per agreement type. Columns record the sales base formula, royalty rate, ad fund rate, minimum amount, due date, grace days, late fee rule and contract clause number. A final column notes who may approve waivers.
Open a blank worksheet to printQuestions owners ask
Should royalty be charged on gross or net sales?
Whatever the signed agreement says. If the wording is vague, fix it at the next renewal and apply one reading consistently in the meantime so no outlet is treated differently.
Can software handle different rules for different outlets?
Yes. Each outlet carries its own base, rate, minimum and fee terms, and the statement applies them automatically from the agreement stored against that outlet.
How do we handle a franchisee who disputes a statement?
Show the daily sales and the rule applied. Most disputes end there. Genuine corrections go through a credit note carrying an approver and a written reason, so the next statement shows exactly what changed and who agreed.