In this guide 6 sections
Write every scheme as a rule with a product list, a period, a slab and a settlement method. Apply it at invoice time, not by memory. Issue a credit note only against a matched invoice and rule number. Review claims against scheme cost every month.
Write each scheme as a rule, not a message
Most leaks begin with a WhatsApp forward. A scheme lives in a photo of a circular, and three salesmen read it three ways, so one gives the free carton on the first order. Another waits for the month total. A third rounds up.
Give each scheme a rule number and one page stating products, stockist class, dates, slab, benefit and settlement method, plus whether it stacks with other running schemes. Too long means too loose.
The sales manager owns the wording, and finance signs it off before a single salesman, distributor or stockist sees the scheme in print.
- Rule number and name
- Eligible product codes and pack sizes
- Stockist class or territory
- Start date, end date and grace period
- Stacking and exclusion notes
Slab, free-quantity and festival schemes behave differently
Slab schemes leak at the boundary. A stockist who orders just below the slab asks for a top-up invoice later, and the rule must say whether that late invoice counts.
A free-quantity scheme gives units, not money. Ten cartons and one free sounds simple until returns arrive, when you must decide if the free carton returns with the paid ones and how stock value treats it.
Festival schemes run short and stack on top of the standing terms, so they create most of the month-end disputes between stockists and the accounts desk. Fix the cutoff by invoice date. Never use delivery date.
- Slab: count by invoice, by month or by quarter
- Free quantity: booked as stock out at zero rate
- Festival: invoice date decides eligibility
- Returns: benefit reversed in proportion
Apply the scheme at billing, not afterwards
Billing is where a rule costs least to enforce, because once the invoice screen picks the scheme from product and stockist class, the salesman cannot invent one. Free items appear as their own lines at zero price, so stock still reconciles against the warehouse count at the next stock take.
Where schemes settle later, as a credit note after the slab is met, the system should accrue the likely claim as each invoice is raised. Finance then sees the liability building. No surprise lump lands at quarter-end.
Never let a credit note be typed freehand, because it should pick a rule number and a list of invoices from the system instead.
Tie every credit note to an invoice and a rule
A clean credit note has four anchors: the stockist, the rule number, the invoices that earned it and the calculation line by line. If any is missing, hold the note.
Check the arithmetic against the rule. Total the eligible quantity, apply the slab and compare the result to the claimed amount, then send differences back to the salesman with the page of the rule attached.
Audit a sample every month. Pick five credit notes and walk each one back through its invoices to the rule, noting every quantity, date or signature that does not match.
- Stockist code and rule number on the note
- Invoice numbers listed with eligible quantity
- Calculation shown line by line
- Approver name and date
- Settlement: credit note, cash or free stock
Review leaks once a month
Compare scheme cost with the sales it drove, then look for stockists whose claims outpace orders and for products where free stock is all that moves.
Close each rule when it ends. An open rule keeps paying. Start with your three biggest schemes and check them against last month’s credit notes, flagging any without a rule number or an invoice list.
Scheme rule card and claim check
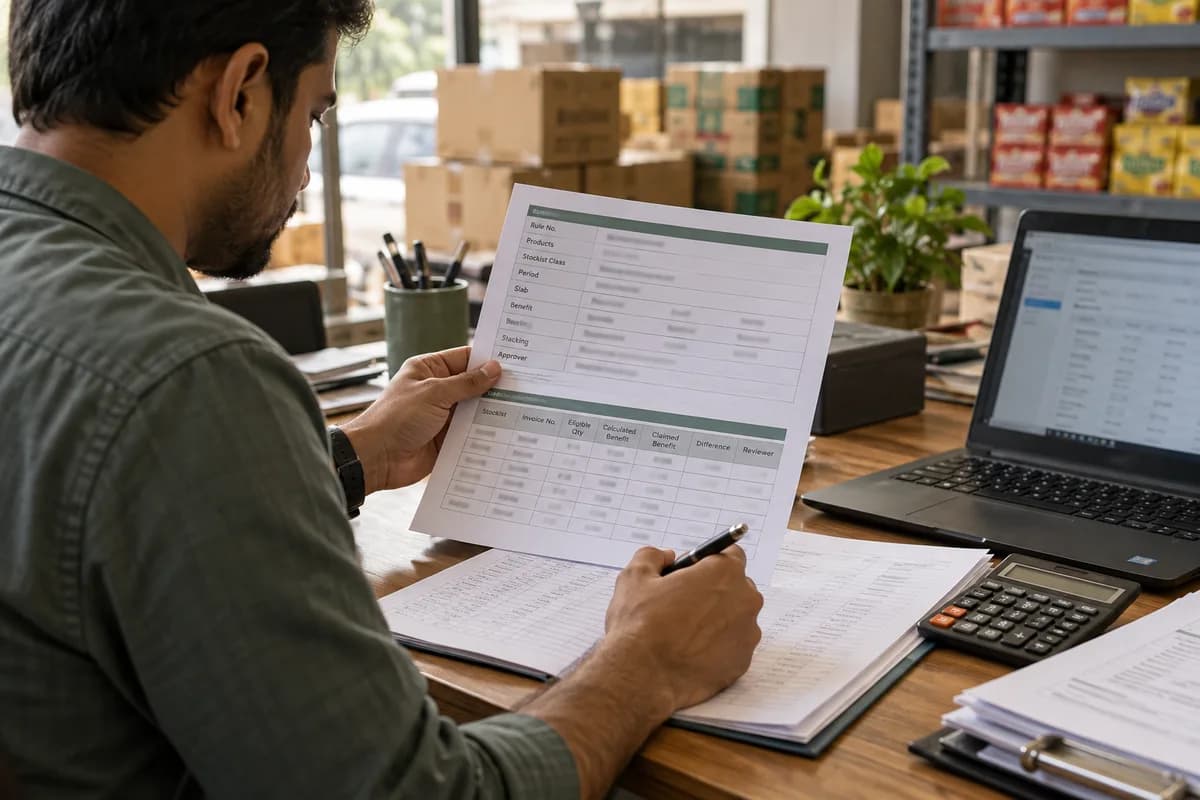
A one-page template in two halves. The top half is the rule card with rule number, products, stockist class, dates, slab table, benefit, stacking note and approver. The bottom half is the claim check, a table of stockist, invoice numbers, eligible quantity, calculated benefit, claimed benefit, difference and reviewer initials.
Open a blank worksheet to printQuestions owners ask
How do we stop salesmen offering unwritten schemes?
Let the invoice screen pick the scheme. If a benefit is not in a written rule, it cannot be billed, and any exception needs a named approver and a reason recorded against the invoice. No rule, no discount. Salesmen soon learn the pattern.
Should free stock be booked at zero rate?
Many distributors do, for unit tracking. The cost is carried by the paid lines, so agree the method with your accountant before the first invoice, otherwise stock value and margin reports will disagree. Consistency matters here. Write the method down.
What if a stockist returns goods after earning a slab benefit?
The rule should say so in advance. Usually the benefit is recalculated on the net quantity and the difference is adjusted in the next credit note, so heavy returns cancel the slab. Write it into the rule. Decide before the festival.
How often should schemes be reviewed?
Review each scheme when it ends. Check open ones monthly against the credit notes issued, and give long-running standing terms a proper yearly look, since old terms drift from current prices and pack sizes. Old rules linger quietly.