Invoice Management for Garment wholesalers
Bill trade garment supply using the accepted piece or pack basis and keep account adjustments traceable.
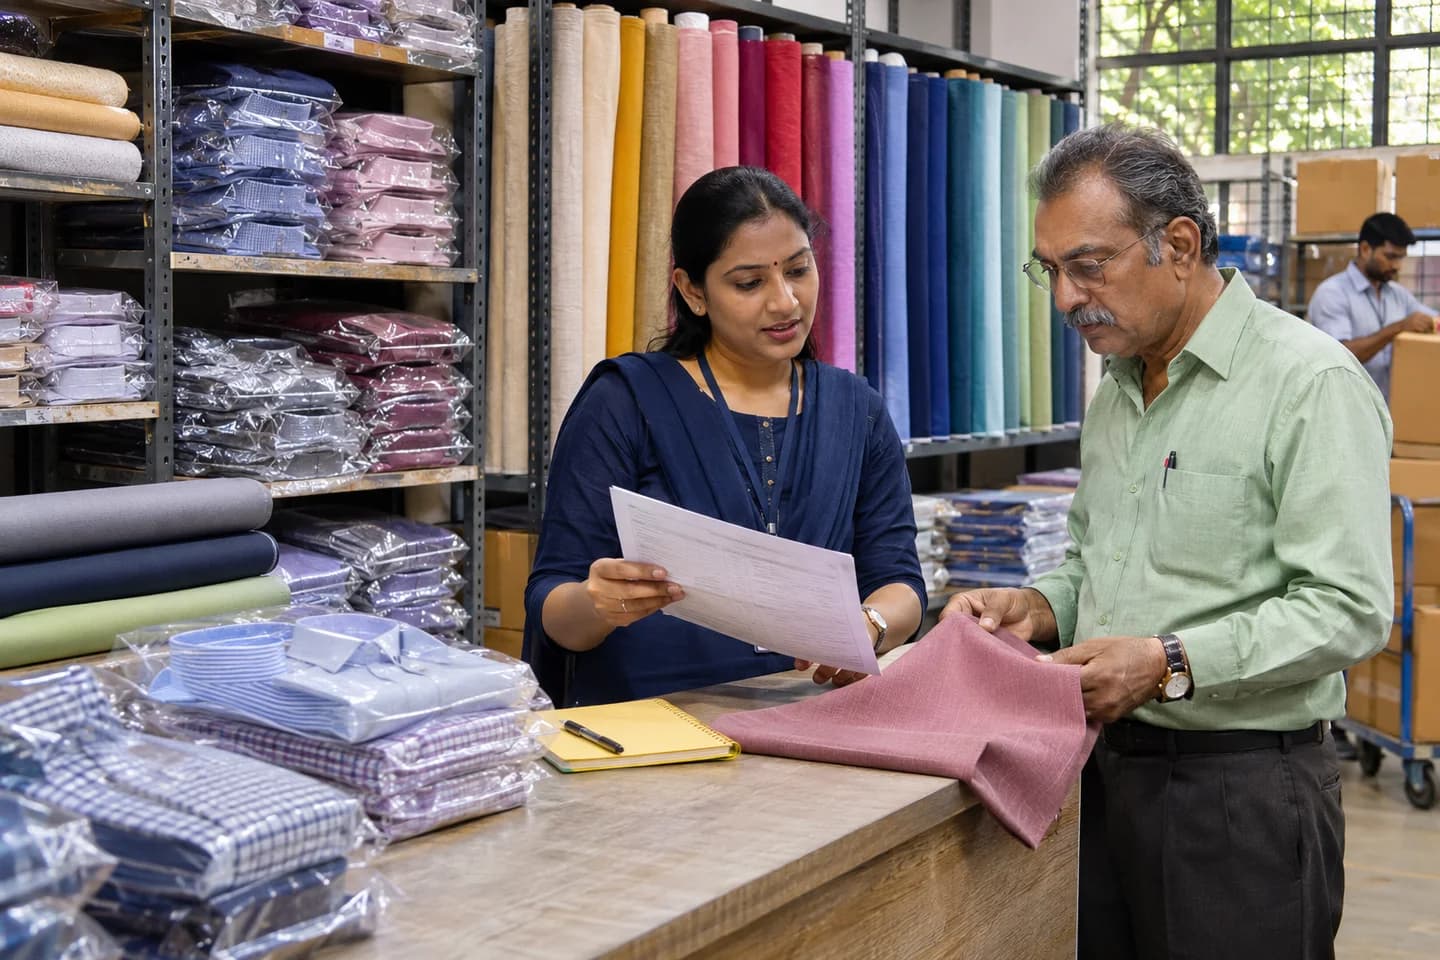
Does this function belong in your operation?
Use when wholesale bills must reconcile garment packs, variant quantities, split supplies and trade-account adjustments.
A garment supply or agreed billing event is authorised for invoicing.
Bill the accepted garment supply using the agreed piece or pack price basis and retain the underlying variant quantities. A carton count is not a garment quantity, and a partial dispatch should not silently bill the whole assortment. Keep discounts, freight, advances and approved credits identifiable. An agent's authority to collect and the evidence of customer payment must be distinguished from the agent's later remittance.
Bring the records the workflow depends on.
- Purchasing entity, payer and approved billing details
- Accepted variant quantities and selling-unit definitions
- Supply evidence, agreed rates, discounts and freight
- Advance, receipt and approved credit references
Outputs to check
- Garment supply invoice register
- Piece and pack billing reconciliation
- Buyer balance with separately identified disputed amounts
Follow the invoice management workflow.
Use this sequence to compare your current process with the proposed module. Agree the owner, permission and exception at each step.
Who uses the module, and who approves?
Keep responsibilities distinct even when one person holds more than one role.
Decide how exceptions are handled.
These business rules belong in configuration and testing. A normal transaction alone does not demonstrate that the workflow is ready.
Can this work independently?
Invoicing can use entered approved supply lines without a connected order module. Product definitions establish units; order and dispatch records substantiate billable quantities. Receipts, credits and refunds have separate execution records. Pending remittance by an authorised collecting agent alone is not a reason to charge the customer again.
Systems and records it connects with
- Product and order records: Accepted garment units, variant quantities and price basis.
- Sales returns: Approved credit quantities and original supply references.
- Receipts and accounting: Customer payments, agent collections and authorised adjustments.
Configure, test and introduce the workflow.
- Compare actual piece-priced and pack-priced invoices with their carton and order records.
- Have accounts test a split dispatch, an advance allocation and a credit against an already paid bill.
- Agree numbering, billing authority and the opening account reconciliation before using the reviewed workflow for new invoices.
Check the result before rollout.
Apply these checks to a sample from the agreed workflow, then repeat with an exception. Keep the expected result beside the test record.
- Each invoice line reconciles to its agreed garment unit and authorised billing quantity.
- Partial deliveries and advances do not create duplicate billing or payment allocations.
- Credits and confirmed receipts explain the remaining customer balance.
How the business operates.
A garment wholesaler supplies finished clothing to retail shops, boutiques, resellers or other trade buyers. A sale can be a fixed pack containing a declared size ratio, an agreed assortment, or individual size and colour variants. The order therefore needs more than a design photograph and total piece count. Sales, stores and billing must agree what one pack contains, what has actually been reserved and which substitutions the buyer accepted. This scope covers physical wholesale supply. It shares receiving, dispatch and credit work with other distributors, but its distinctive control is the garment variant and pack composition. Fabric production, garment stitching and consumer retail are separate operating models. Supplier-owned or customer-owned goods held on the premises retain their declared ownership and custody references.
The records that hold the operation together.
- Style and variant register: supplier reference, garment description, labelled size, colour, approved photo, selling unit and pack composition version.
- Buyer order: purchasing account, authorised contact or agent, accepted variants, quantity in pieces and packs, price basis, credit decision and dispatch instructions.
- Stock movement record: declared owner, source document, location, intact or opened pack, loose-piece count, reserved quantity and inspection hold.
- Packing and handover record: order revision, contents per carton, shortages, accepted substitutions, receiver or carrier and acknowledgement reference.
Operational bottlenecks to check
A full carton has the wrong size mix
A piece total can reconcile while the retailer is missing the sizes it ordered. Keep the variant quantities behind each pack and check them at the packing handoff.
Opened packs disappear into a total
Selling loose pieces from a pack changes the assortment available for the next buyer. Record the conversion so the same contents are not counted as both a complete pack and loose stock.
How work flows across this business
This module sits within a wider operating process. Use the sequence to identify the other teams and records affected by a change.
1. Define what is offered
Review the actual supplier range and confirm whether each design sells in fixed packs, mixed assortments or individual pieces. Distinguish available stock from an unconfirmed future supply request.
2. Confirm the retailer's assortment
Record the buyer's sizes, colours and quantities with the agreed commercial terms. A message asking for a design is an enquiry until the authorised buying contact confirms the order.
3. Check supply and release
Compare variant-level availability with existing reservations and credit decisions. A customer order does not establish supplier acceptance, and a supplier estimate does not establish a dispatch date.
4. Pick and check the mix
Allocate the approved pieces or intact packs, check their contents and retain short sizes on the open order. Obtain buyer agreement before changing a colour, size ratio or delivery split.
5. Dispatch and bill the agreed supply
Record carton contents and the actual handover, then use the agreed billing basis. Keep goods dispatched, goods acknowledged by the buyer and quantities still disputed as separate facts.
6. Resolve the remaining balance
Reconcile unfulfilled lines, accepted cancellations, receipts and any return decision. Receiving a parcel back does not itself approve a credit, resale of its contents or payment of a refund.
Industry reports to connect with
- Open orders by style, colour and size, with shortages separated from buyer-approved cancellations.
- Intact packs and loose pieces by location, including reservations, held returns and unexplained count differences.
- Dispatched quantities against carton acknowledgements, billed lines and unresolved shortage claims.
- Return reasons and approved outcomes by supplied variant, with outstanding credits or refunds shown separately.
Questions before implementation.
When should garment wholesalers consider invoice management?
Use when wholesale bills must reconcile garment packs, variant quantities, split supplies and trade-account adjustments. A garment supply or agreed billing event is authorised for invoicing.
What should we bring to the requirements discussion?
Bring anonymised examples of Purchasing entity, payer and approved billing details; Accepted variant quantities and selling-unit definitions; Supply evidence, agreed rates, discounts and freight; Advance, receipt and approved credit references. Show who creates, checks and changes each record. Use only records from an activity that meets the suitability conditions above.
Does this replace our existing business software?
The starting point is your current system and the gap you need to close. Bill trade garment supply using the accepted piece or pack basis and keep account adjustments traceable. Configuration, a connected module or a custom build are evaluated against that gap before a replacement is proposed.
What is outside this module?
The accounting owner determines tax treatment and statutory documents. An invoice is not evidence that garments were delivered, the buyer accepted their condition or money was received.
How are scope, price and rollout decided?
The proposal follows a review of your records, user roles, branches and existing software. Data migration, connections, training and support are scoped separately where needed. Each invoice line reconciles to its agreed garment unit and authorised billing quantity. Use this check when reviewing the first working version.
Related functions for garment wholesalers.
Discuss invoice management for your business.
Tell us which workflow needs attention and which systems your team uses. The next step is a requirements discussion and a written scope.
What happens after you share your requirements
- We review your brief and the systems you already use.
- We clarify the workflow, missing information and the work to consider first.
- The proposed scope sets out the deliverables, responsibilities and dependencies.
- Review the scope and commercial terms before deciding whether to proceed.
Start with your requirements
Describe your current process, the people involved and the change you need. Start with the details you know; we can clarify the rest together.
Share your requirements