Business solutions for Last-mile delivery companies
Explore software for work such as “Merchant parcel intake and custody reconciliation”. Review each business function below, including when it fits and what to check before implementation.
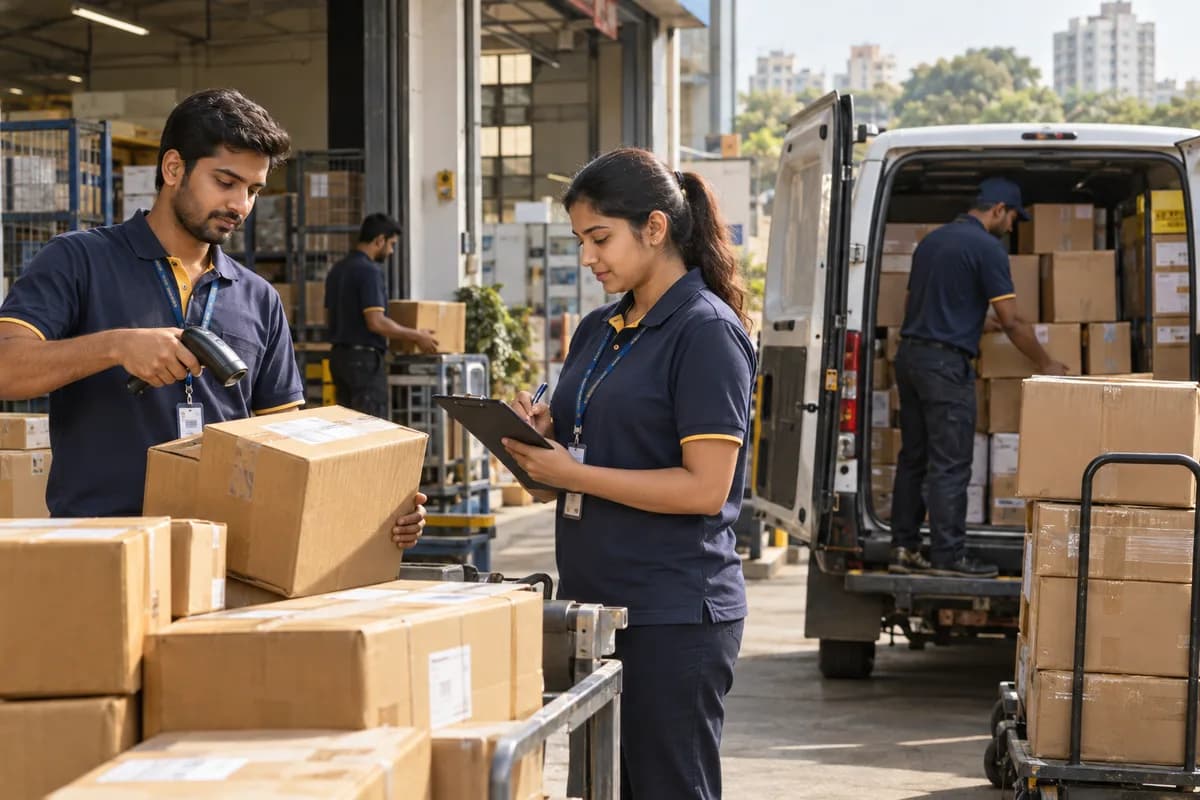
How the business operates.
A last-mile delivery company takes custody of a merchant’s parcels at a hub or pickup point and coordinates their delivery attempts and authorised returns. The goods are entrusted for delivery under the accepted merchant instructions and remain outside operator-owned stock; the delivery operator manages the service and custody records. This proposed software scope connects merchant instructions, actual parcels, rider assignments, attempt evidence and commercial reconciliation. Where cash on delivery is contracted, money collected for the merchant must remain separate from the operator’s delivery-service revenue. A completed rider task can represent a failed attempt, so delivery, return and cash outcomes need their own evidence.
The records that hold the operation together.
- Merchant order and accepted delivery-service reference
- Parcel identifier, expected and actual piece counts and custody acknowledgements
- Recipient instructions and authorised changes with access restrictions
- Rider assignment, attempt outcome and supporting evidence
- Approved reattempt or return instruction and merchant receipt
- Contracted collection amount, verified payment and current custodian
- Merchant remittance reconciliation and separate service invoice
Operational bottlenecks to check
Assignment changes but parcels stay with the first rider
A reassigned task is not a custody transfer. Both workers’ acknowledgements and unresolved parcels need to remain visible.
A closed attempt appears as a delivery
Failure, refusal and incomplete evidence need explicit outcomes. A closed work item must not inflate the delivered-parcel count.
Returned status precedes actual receipt
The merchant’s return instruction and the parcel reaching its recipient are different events. Retain the physical return acknowledgement and any discrepancy.
Collected cash becomes assumed revenue
Cash received for merchandise belongs to the merchant’s settlement record. Internal handover and service-fee deductions must not create a second receipt or an unsupported reduction.
Follow the work across teams.
This is a planning flow. Confirm the steps, owners and approval rules against your actual operation.
Roles and responsibility boundaries.
Reports your managers need.
- Parcels by merchant, custodian and unresolved mismatch
- Unassigned work and attempts awaiting review or instructions
- Delivered, failed, reattempted and physically returned parcels
- Collection differences by rider, payment evidence and merchant
- Remittances pending or evidenced separately from service receivables
Connections to scope
- Assess authorised merchant-order imports, delivery-evidence exports and accounting references using agreed parcel and account identifiers.
- Rider apps, geolocation, notifications and payment connections require separately agreed supported scope. Evidence access and retention need review before collecting recipient photographs or signatures.
Confirm data access, record ownership and the exchange method for each connection. Inclusion here does not mean every connection is available in a standard package.
Setup decisions and adoption risks.
Use these requirements to plan phases, data migration and user training. Agree the release sequence after reviewing your current systems.
Limitations to settle before implementation
- This example covers ordinary parcel delivery. Medicines, temperature-controlled goods, hazardous items and specialised bulky-item handling require separately confirmed capability and obligations.
- A task status, photograph or signature is evidence to review, not independent proof of parcel contents, rightful receipt or payment settlement.
- Live tracking, route optimisation, emergency response, insurance decisions and delivery-time commitments are not supplied by these proposed records.
Modules to consider first.
These functions connect to the operating model above. Confirm each one against the work your business actually runs.
Choose the operation you want to improve.
Use these activities to explain your scope. Your business does not need every function in the directory.
- Merchant parcel intake and custody reconciliation
- Rider assignment and delivery-attempt recording
- Authorised reattempt and physical return handover
- Contracted collection reconciliation and separate delivery-service billing
Explore the business functions.
Production, stock, fleet and recurring billing functions apply only where your business runs those activities. Read the suitability conditions on each page.
Finance & Accounting
CRM
Field Service
Project Management
Start with the problem your team can describe.
Bring a sample record and show where information is copied, missed or waiting for approval. Scope the first useful change from there.
What happens after you share your requirements
- We review your brief and the systems you already use.
- We clarify the workflow, missing information and the work to consider first.
- The proposed scope sets out the deliverables, responsibilities and dependencies.
- Review the scope and commercial terms before deciding whether to proceed.
Start with your requirements
Describe your current process, the people involved and the change you need. Start with the details you know; we can clarify the rest together.
Share your requirements