Purchase Order Management for Bakeries
Record authorised supplier orders and track what remains due.
Does this function belong in your operation?
Use when purchasing commitments need control before delivery and billing.
The business agrees to purchase goods or services.
Flour and fat support the bake plan, while fresh cream, cake boxes and decorations can be required for named cake commitments. Order the right item and pack size against the authorised requirement. Receiving staff confirm quantities and condition separately; a purchase line must not make ingredients appear available for production before they have been accepted.
Bring the records the workflow depends on.
- Ingredient or packaging requirement from the bake plan, reorder list or confirmed custom-cake work.
- Supplier item, pack size and quantity with the specification needed by the bakery.
- Agreed rate, delivery location and the manager responsible for purchasing approval.
- Goods-receipt and supplier-bill references used to reconcile the commitment.
Outputs to check
- Authorised supplier order distinguishing ingredients from cake-packaging requirements.
- Unfulfilled purchase list identifying the bake or cake requirement affected by a shortage.
Follow the purchase order management workflow.
Use this sequence to compare your current process with the proposed module. Agree the owner, permission and exception at each step.
Who uses the module, and who approves?
Keep responsibilities distinct even when one person holds more than one role.
Decide how exceptions are handled.
These business rules belong in configuration and testing. A normal transaction alone does not demonstrate that the workflow is ready.
Can this work independently?
Purchase orders can run as a controlled register with entered supplier and item data. Goods receipt owns physical acceptance, accounts payable owns invoice matching and posting, and the payment process owns settlement. Connecting those records provides closure evidence; issuing a PO performs none of those later actions.
Systems and records it connects with
- Goods receipt: Counted, accepted and rejected supplier-delivery quantities.
- Stock tracking and alerts: Item-location quantities and authorised stock movements.
- Vendor management: Approved supplier identities, terms and sensitive-change controls.
- Your accounting software: Posted financial entries and reconciliation references.
Configure, test and introduce the workflow.
- We follow how items are requested, ordered and received. You provide recent orders and supplier lists. A summary note comes back.
- Rates, credit periods and freight terms are entered for each supplier. The purchase assistant checks them. Stock levels that trigger an order are set item by item. The owner approves the list.
- New orders are raised on screen while the old method runs. Differences are explained and corrected. Storekeepers receive on phones and accounts match bills. Old order books are closed.
Check the result before rollout.
Apply these checks to a sample from the agreed workflow, then repeat with an exception. Keep the expected result beside the test record.
- A partial packaging delivery does not make the related cake requirement appear completely supplied.
- The reviewer can distinguish the supplier's accepted pack size from the bakery's internal consumption unit.
- The PO references receipt and bill decisions without performing either or initiating a payment.
How the business operates.
A bakery sells bread, puffs and cakes over the counter, takes birthday cake orders by phone and fulfils delivery-platform orders. Each of these channels keeps its own record of what was sold.
The records that hold the operation together.
- Recipe costing from your own ingredients. Each product carries its recipe: ingredient quantities, yield per tray and the loss you expect in baking. With the latest supplier rate beside each ingredient, the ingredient cost of a tray and of a single piece can be read off. Labour, gas and packing are your own add-on rates, set once. When butter or cocoa moves, the cost view moves with the rate.
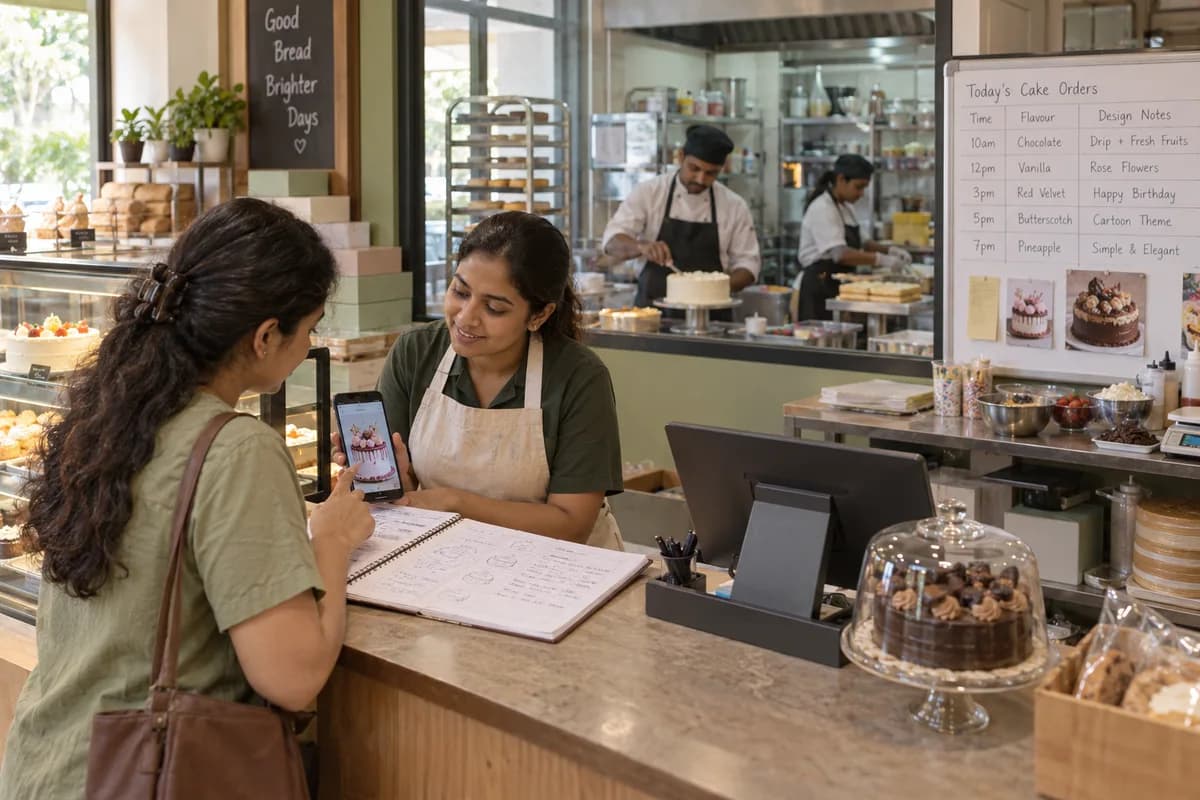
- Custom cake orders. Each cake slip records flavour, weight, inscription, design notes, advance paid, balance and pickup time. The counter reads out status to a caller. The kitchen sees which cakes are due today and which need a name piped. Repeat orders are copied from the last one.
- Daily production planning. Confirmed cake orders, standing café and hotel orders and your usual weekday counter quantities are added into one list of trays per item. The head baker loads the ovens from it. Unsold and binned stock at close feeds the next plan.
- Ingredient inventory. Flour, sugar, butter, cream and boxes fall as batches are logged, each with a reorder level. The plan is checked against the store the evening before, and a shortfall raises a purchase order to the supplier. Spoiled or dropped stock is recorded as wastage.
Operational bottlenecks to check
Custom cake orders are missed
An order is taken at one outlet while the design photo reaches a chef who is off that day. The customer arrives for a cake that was not made. The advance goes back.
Production is planned by estimate
Without sales by item and day, the kitchen guesses. Some items sell out by noon while others sit on the shelf. Waste and stock-outs happen together.
How work flows across this business
This module sits within a wider operating process. Use the sequence to identify the other teams and records affected by a change.
1. Recipes are costed
Each recipe is entered with quantities and yield, and priced from the latest supplier rate. When a rate changes, the cost per tray changes, and the owner sees which products need a new price before the next festival rush.
2. Orders are booked
Record custom cake orders with flavour, weight, inscription, design notes, advance paid and pickup time at the counter, while café and hotel orders sit in the same list.
3. The production plan is built
Confirmed orders, standing wholesale orders and the usual counter quantities are added together into one list, and the head baker reads trays per item before loading the ovens.
4. Ingredients are checked
The plan is matched against store stock for flour, sugar, butter and cream, and any shortfall raises a purchase order to the flour or dairy supplier the same evening. Nothing is ordered twice.
5. Batches are logged
Each batch is recorded with product, quantity, make date and the baker’s name, which leaves a record that survives the end of the day. The board can stay clean.
6. Selling, delivery and closing
The counter bills from the same item list, and every wholesale round leaves the van with a bill for each café. Unsold stock and wastage are entered at closing so tomorrow’s plan starts from what actually happened.
Industry reports to connect with
- Sales by product, by outlet and by hour of the day
- Wastage and unsold stock by product and by day
- Custom cake orders due today and this week
- Café, hotel and canteen dues outstanding
Questions before implementation.
When should bakeries consider purchase order management?
Use when purchasing commitments need control before delivery and billing. The business agrees to purchase goods or services.
What should we bring to the requirements discussion?
Bring anonymised examples of Ingredient or packaging requirement from the bake plan, reorder list or confirmed custom-cake work.; Supplier item, pack size and quantity with the specification needed by the bakery.; Agreed rate, delivery location and the manager responsible for purchasing approval.; Goods-receipt and supplier-bill references used to reconcile the commitment. Show who creates, checks and changes each record. Use only records from an activity that meets the suitability conditions above.
Does this replace our existing business software?
The starting point is your current system and the gap you need to close. Record authorised supplier orders and track what remains due. Configuration, a connected module or a custom build are evaluated against that gap before a replacement is proposed.
What is outside this module?
A purchase order does not confirm supplier acceptance or physical receipt.
How are scope, price and rollout decided?
The proposal follows a review of your records, user roles, branches and existing software. Data migration, connections, training and support are scoped separately where needed. A partial packaging delivery does not make the related cake requirement appear completely supplied. Use this check when reviewing the first working version.
Related functions for bakeries.
Discuss purchase order management for your business.
Tell us which workflow needs attention and which systems your team uses. The next step is a requirements discussion and a written scope.
What happens after you share your requirements
- We review your brief and the systems you already use.
- We clarify the workflow, missing information and the work to consider first.
- The proposed scope sets out the deliverables, responsibilities and dependencies.
- Review the scope and commercial terms before deciding whether to proceed.
Start with your requirements
Describe your current process, the people involved and the change you need. Start with the details you know; we can clarify the rest together.
Share your requirements