Sales Returns and Credit Notes for Building material distributors
Record returned building materials and their separate stock, customer-credit and supplier-claim decisions.
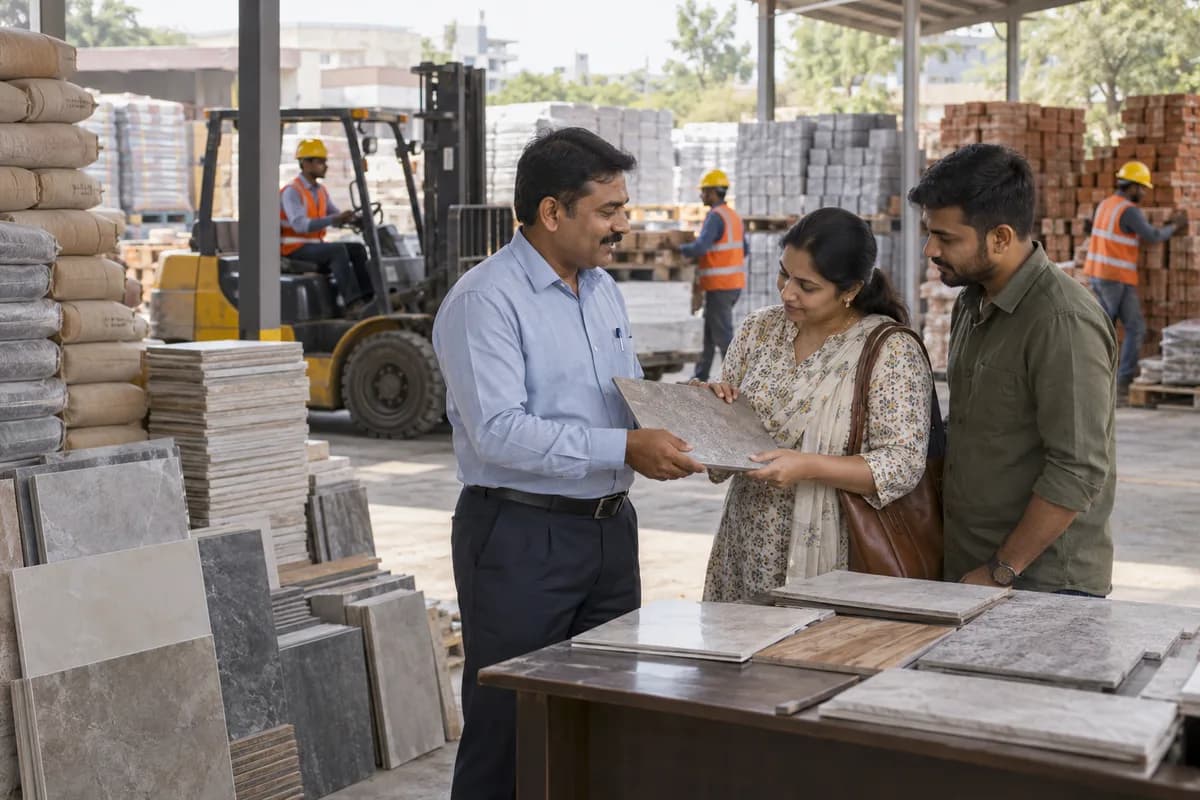
Does this function belong in your operation?
Use where site deliveries or dealer supplies produce surplus, damage or specification-related return requests that need quantity and account reconciliation.
A buyer reports surplus, damaged or incorrectly supplied material against an identifiable sale.
Surplus material and a damaged delivery require different evidence. Link the request to the original item and site, record the quantity received and preserve package or batch details. A broken tile carton or opened bag must not silently reappear as saleable stock. The commercial credit decision, supplier claim and refund execution remain separate, including when the original invoice has already been paid.
Bring the records the workflow depends on.
- Original order, invoice and site delivery references
- Requested item quantities and return reason
- Actual package, batch or shade identifiers where relevant
- Commercial acceptance rules and condition evidence
- Approved financial and stock-disposition responsibilities
Outputs to check
- Sale-linked return request and physical receipt history
- Quantity disposition and stock-handoff record
- Approved credit or refund instruction with unresolved supplier claims
Follow the sales returns and credit notes workflow.
Use this sequence to compare your current process with the proposed module. Agree the owner, permission and exception at each step.
Who uses the module, and who approves?
Keep responsibilities distinct even when one person holds more than one role.
Decide how exceptions are handled.
These business rules belong in configuration and testing. A normal transaction alone does not demonstrate that the workflow is ready.
Can this work independently?
A return can be recorded manually using the original sale or a documented exception. Stock posts the approved condition and quantity; accounts issues the financial document. Collection costs or restocking adjustments require the actual agreement and approval. A supplier credit does not prove that a customer refund was executed.
Systems and records it connects with
- Orders and invoices identify the sold line, site, quantity and payer.
- Stock receives authorised quantities with their actual condition and retained batch references.
- Accounts and supplier-claim records reconcile customer adjustments and recovery separately.
Configure, test and introduce the workflow.
- Compare examples of surplus stock, damaged delivery and supplier-direct returns with sales, godown and accounts.
- Trial a partly accepted carton and a paid invoice, checking that physical receipt, credit and refund remain separate.
- Reconcile open claims and held material before using new reason codes and approval rules for subsequent returns.
Check the result before rollout.
Apply these checks to a sample from the agreed workflow, then repeat with an exception. Keep the expected result beside the test record.
- Requested, received and commercially accepted return quantities remain distinguishable.
- A damaged or uncertain return cannot automatically restore saleable stock.
- Customer credits, supplier claims and executed refunds have distinct references.
How the business operates.
A contractor orders cement for one site and matching tiles for another, but the billing account belongs to the same firm. Keep the site instruction beside the customer commitment. Building-material distributors buy and supply their actual range of cement, tiles, pipes, paints, fittings or other building products through yards, godowns and counters. A product listed for supply is not necessarily held locally. Supplier-direct delivery needs its own confirmation and receipt evidence. The workflows below describe stock distribution and site fulfilment; brokerage-only businesses need a different stock scope. Brand appointment, installation capability and technical suitability are established separately from the item record.
The records that hold the operation together.
- Customer account with separate site, purchaser and receiving-contact references
- Item code, brand, variant, pack quantity and approved unit conversion
- Supplier acknowledgement and actual goods-receipt differences
- Tile carton shade or batch markings where the supplied line requires them
Operational bottlenecks to check
The same product name hides different stock
A tile series can have different carton markings, while pipe descriptions can hide size or joint variants. Product identity and the actual package details need to survive the handoff from counter to godown.
A mixed order is mistaken for one completed load
Some lines leave from the yard and others come from a supplier. Each route needs evidence of the supplied quantity; a complete cement delivery cannot close an outstanding fitting line.
How work flows across this business
This module sits within a wider operating process. Use the sequence to identify the other teams and records affected by a change.
1. Identify the material and site
Capture the requested product from the actual specification or prior order. Do not substitute a similar pipe or tile simply because the description looks familiar. Resolve incomplete units before pricing.
2. Agree supply and commercial terms
Check available or supplier-confirmed quantities, the accepted rate, payer and delivery scope. Record whether transport and unloading are included. A requested delivery date remains distinct from a confirmed arrangement.
3. Release the relevant lines
Review credit and reserve the stock that is actually available. Split a mixed order where the buyer accepts staged supply, retaining each line’s destination and outstanding quantity.
4. Record what reaches the site
Match the loading list with the recipient’s evidence. Short supply, breakage or a refused delivery needs its own record; do not close a full order from a single lorry departure.
5. Reconcile billing and returns
Pass the agreed billable quantities to accounts. Receive returned goods into the appropriate condition state and obtain the commercial credit decision separately. Keep the unpaid or disputed balance visible after delivery is complete.
Industry reports to connect with
- Open quantities by customer, site and delivery source
- Saleable, reserved and held stock by item and location
- Unmatched delivery acknowledgements and reported shortages
- Customer exposure across site references and authorised releases
Questions before implementation.
When should building material distributors consider sales returns and credit notes?
Use where site deliveries or dealer supplies produce surplus, damage or specification-related return requests that need quantity and account reconciliation. A buyer reports surplus, damaged or incorrectly supplied material against an identifiable sale.
What should we bring to the requirements discussion?
Bring anonymised examples of Original order, invoice and site delivery references; Requested item quantities and return reason; Actual package, batch or shade identifiers where relevant; Commercial acceptance rules and condition evidence; Approved financial and stock-disposition responsibilities. Show who creates, checks and changes each record. Use only records from an activity that meets the suitability conditions above.
Does this replace our existing business software?
The starting point is your current system and the gap you need to close. Record returned building materials and their separate stock, customer-credit and supplier-claim decisions. Configuration, a connected module or a custom build are evaluated against that gap before a replacement is proposed.
What is outside this module?
Applicable return obligations, tax treatment and refund decisions use the business’s adviser-approved rules. The record does not diagnose a construction defect or establish manufacturer liability.
How are scope, price and rollout decided?
The proposal follows a review of your records, user roles, branches and existing software. Data migration, connections, training and support are scoped separately where needed. Requested, received and commercially accepted return quantities remain distinguishable. Use this check when reviewing the first working version.
Related functions for building material distributors.
Discuss sales returns and credit notes for your business.
Tell us which workflow needs attention and which systems your team uses. The next step is a requirements discussion and a written scope.
What happens after you share your requirements
- We review your brief and the systems you already use.
- We clarify the workflow, missing information and the work to consider first.
- The proposed scope sets out the deliverables, responsibilities and dependencies.
- Review the scope and commercial terms before deciding whether to proceed.
Start with your requirements
Describe your current process, the people involved and the change you need. Start with the details you know; we can clarify the rest together.
Share your requirements