Record every return against its invoice, with a credit note and the stock taken back.
Sales returns record what a customer sends back and what you did about it: a credit note against the original bill, the stock taken in again, and the reason it came. Damaged, wrong size, short-supplied or simply unsold, each is counted apart from the others. The customer’s ledger falls by exactly what came through the gate.
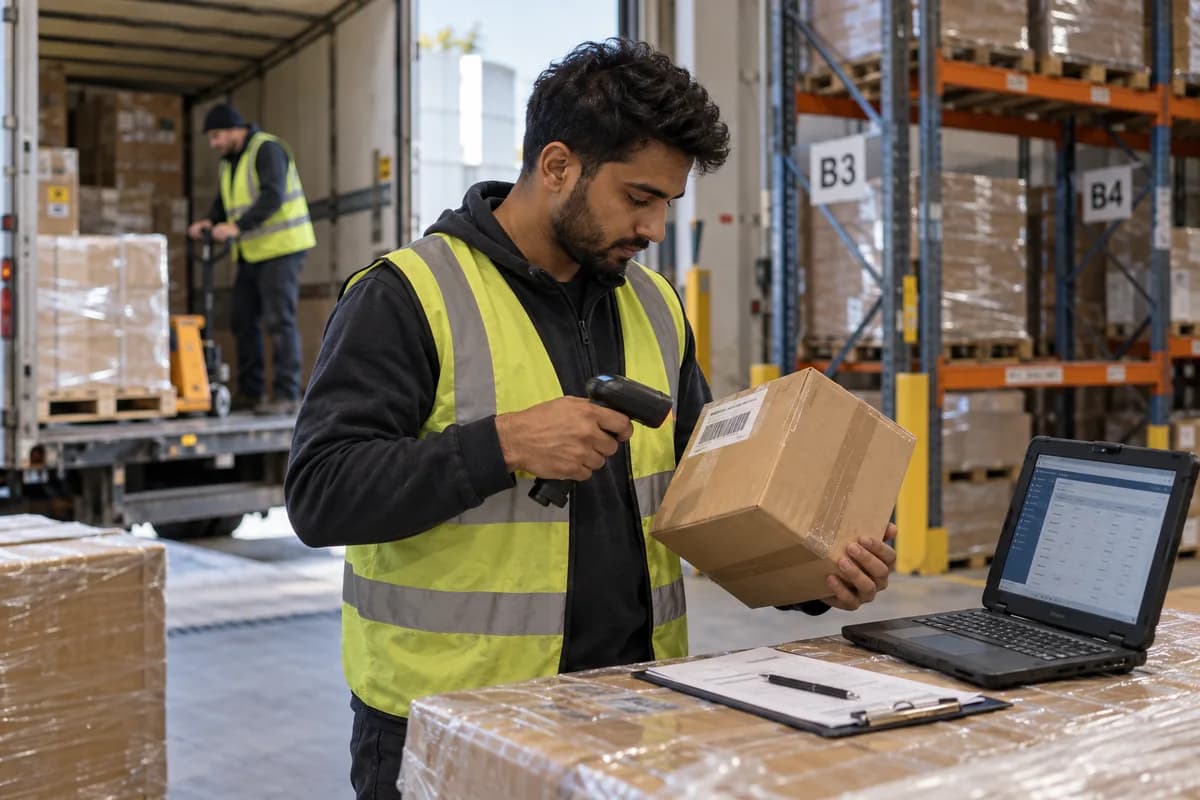
Three bundles of rods return from a site on the same truck that took the next load out. The driver carries no paper for them. The warehouse counts them in, the office hears a week later, and by then the contractor’s ledger and his diary disagree by a four-figure sum.
The return is entered against the invoice it came from, with a reason on each line. The credit note comes from its own series, the stock goes back to the shelf or into a damaged bin, and his account falls by that much. One entry has three effects.
What your team uses today.
The module takes over these, one at a time, so nothing has to stop while it is set up.
- Return notes written in a diary
- Credit notes typed in a document
- Verbal replacement promises
The problems this is meant to ease.
What sales returns and credit notes does.
What this looks like in a working week.
Illustrative scenarios, written to show the shape of the work. They are not accounts of client systems.
The people who open this every day.
From first conversation to daily use.
Following a return today
We trace a return from gate to ledger. You show recent cases, and a written flow is sent back.
Reasons and rules
Reasons and time limits are agreed. You approve the list used in the screens.
Credit note layout
The note is matched to your invoice series and tax details. Accounts proof a sample.
Stock handling
Saleable and damaged bins are set up. The storekeeper tries both paths.
Live use
Returns start here on an agreed day. The owner receives a monthly count.
How you would know it is working.
Record where you stand before it goes live, so the change is measured against your own figures.
- Returns by reason, item and customer
- Credit value issued against invoice value
- Damaged stock awaiting disposal or claim
- Replacements open past their promised date
- Returns accepted outside the allowed time
It is one part of a system, not an island.
A module earns its place by what it passes to the next one. These are the connections we set up most often.
- Invoice management
- Stock
- Credit control
- Quality control
- Your accounting software
Products that include it.
How we would put it in.
Questions owners ask about sales returns and credit notes.
Do we raise a credit note, or does the customer raise a debit note?
Usually you raise the credit note and his debit note is matched against it. The software keeps yours and records his. Which document your books should carry is your accountant’s call and not ours.
Do any of your products handle this?
Yes. Building Material Trading Software takes back bags, rods and fittings from a site with a reason, adds them to yard stock and credits them against the right invoice.
Is a note in the invoice file enough when returns are rare?
For a handful a year, yes. It gives way when a salesman accepts a return without asking, or when the warehouse and the ledger are corrected by two people on two different days.
Can a return be stopped after a certain number of days?
Yes. A window can be set per item or per customer, and anything beyond it waits for approval. Owners usually want a warning and not a refusal, since the customer is standing at the counter. The choice is yours.
What sets the cost of sales returns handling?
Return volume and the sales channels set it. Stock bins and an accounting link add scope. Parts are itemised after we read your invoice format. You choose which to keep.
What decides when it can be used?
Mostly your tax layout and the stock rules. Early use needs return entry, credit notes and stock return. The layout is seen before any calendar is drawn.
Businesses that ask for this.
Modules that work with it.
Tell us how you handle sales returns and credit notes today.
A spreadsheet, a register or another system: say which, and we will tell you plainly what is worth changing.
What happens after you share your requirements
- A senior engineer reads your answers. Nobody phones first.
- Within one business day you get a written note: what we understood, what we would start with, and the questions we still have.
- If it fits, a proposal follows with the order of work, what we need from you and what you receive at each step.
- No call is booked and nothing is paid until you have read the note. Your details stay with us.
Start with your requirements
Seven short steps that tell us what you need. A senior engineer reads them before anyone gets in touch.
Share your requirements