In this guide 6 sections
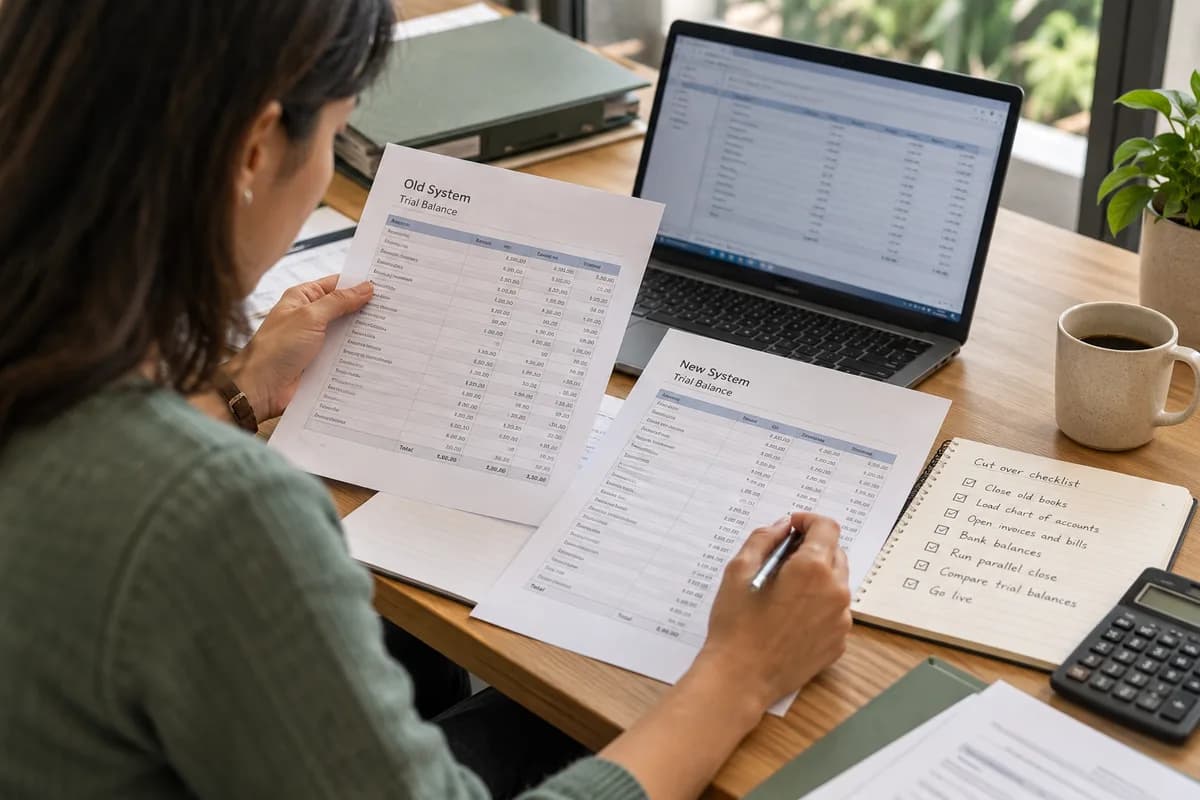
Choose a cut over date at a period end and close the old books. Load the chart of accounts, open invoices, open bills and bank balances, then run one full close on both systems. Go live only when the two trial balances agree, line by line.
Pick a cut over date that suits the books
The cleanest date is the first day of a month, quarter or financial year. Opening balances are then period end balances and nothing is split across the line, whereas a mid month move needs two sets of transactions stitched together by hand.
Count backwards from the date, because you need time to clean master data, load, test and train. Four to six weeks is a sensible lead for a small firm.
Tell the auditor, the bank and your tax adviser early, since they may want copies of the closing trial balance, ageing reports and asset schedule. Ask now.
- Cut over date and the last day in the old system
- Named owner for the old books and the new
- Auditor and tax adviser informed
- Freeze date for new master data
Close the old books properly
Finish the bank reconciliation for every account up to the last day, then post accruals, depreciation and year end entries. Print the trial balance to PDF with the date and time on it.
Chase unapplied receipts and unmatched supplier payments. Do it before anything moves. If a customer paid and the receipt was never applied to an invoice, the open item list will mislead you, so clean it before you copy it across.
Lock the period in the old software. No clerk should edit a closed ledger by habit.
Load the chart, open items and bank balances
Load in a fixed order: chart of accounts first, then customers and suppliers, then tax codes, then opening balances. Sequence matters. Open sales invoices and open supplier bills go in as documents, not as one lump per party, so ageing and reminders still work.
Bank balances load as a single journal per account, equal to the reconciled statement balance, while unpresented cheques and deposits in transit load as separate lines beneath it. Stock value and fixed assets need their own schedules.
Load the asset register with cost, accumulated depreciation and method for each item. Tag numbers help.
- Chart of accounts with mapped group heads
- Open invoices by customer with dates and tax
- Open bills by supplier with due dates
- Bank statement balance plus unreconciled lines
- Stock valuation and fixed asset register
Run one close on both systems
Post the first month in both systems, using the same invoices, receipts and payments, then run a trial balance in both and compare them account by account.
Differences usually come from three places: a tax code mapped to the wrong account, a rounding rule, or an opening item loaded twice. Trace each one to a source document and fix the new system, not the old. Leave the archive alone.
Keep a difference log with the account, amount, cause and fix, and sign it off only when the total reaches zero. No exceptions.
Go live, then retire the old system with care
After the match, announce the switch. Staff stop entering in the old ledger the same hour. Keep it read only, with a backup, for as long as the law or your auditor needs those records.
Run a short training for each role: who posts invoices, who pays bills, who reconciles the bank. Keep it short. Pair the finance lead with the implementer for the first close in the new system, so questions are answered on the spot.
Write the cut over date on the calendar. Then work backwards, task by task, with a name against each.
Cut over runbook
A one page runbook with a dated task list in five blocks: prepare, close, load, parallel close and go live. Each row has the task, owner, due date, source file, check performed and a sign off box. A side table records the old and new trial balance for each account and the difference.
Open a blank worksheet to printQuestions owners ask
Do I need to move every old transaction?
Usually not. Load opening balances and open items, and keep the old data as a read only archive for reference and audit.
How long should the parallel close run?
One full month end is the minimum. Allow a second if tax filings or stock valuation are complex.
What if the trial balances do not match?
Do not go live. Trace each difference to its source document, fix the cause in the new system and rerun the comparison until every account agrees.
Can I cut over mid month?
You can, but it is harder. You must carry invoices and payments across the line and reconcile two partial periods.