Build an insurance system around your renewal dates and your payout statements.
An agency’s income depends on the same customers renewing, year after year, on a date somebody has to remember before the customer does.
Each insurer portal holds one slice of your book. Nobody hands you the whole thing in a single list sorted by expiry date, which is the only order that matters at your desk.
That list, and the claim file behind each customer, is what an agency system is really for. The rest of the modules hang off those two.
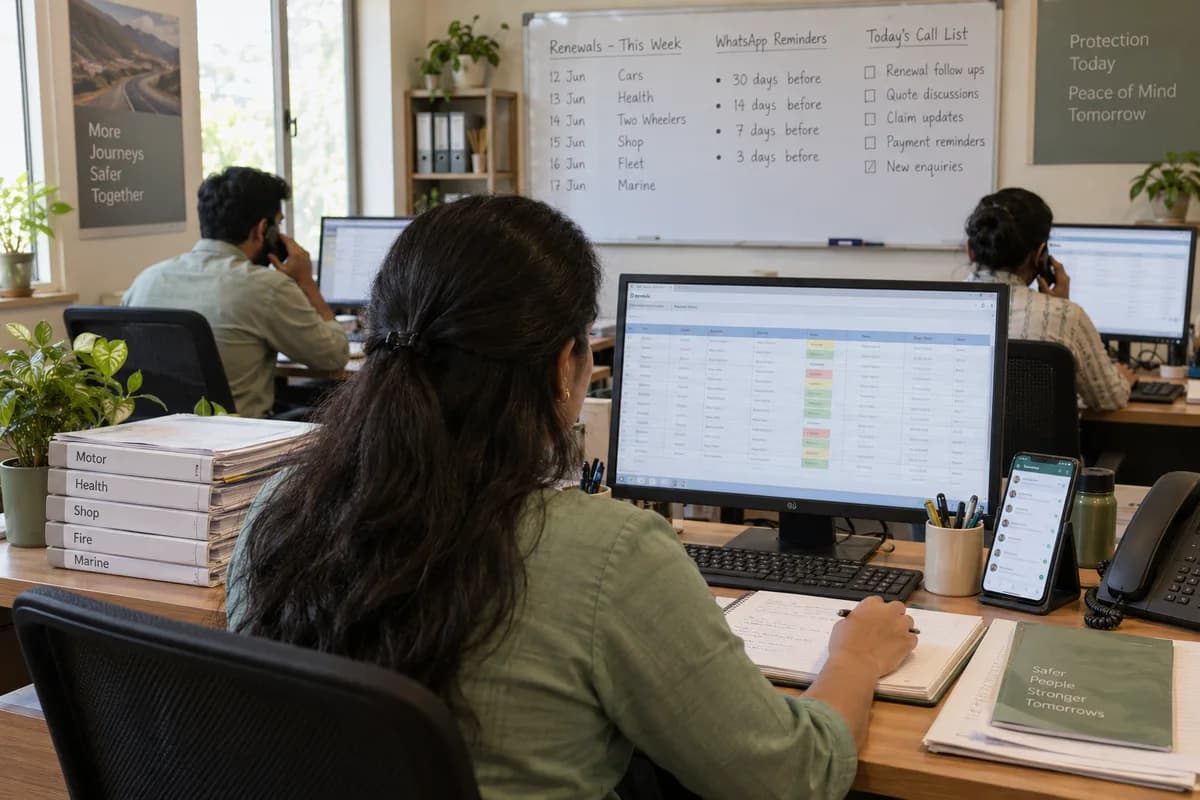
Insurance businesses we can build for.
Motor renewals in their thousands, or a handful of group health accounts worth more than all of them. What gets built depends on the book you actually write.
- General insurance agencies
- Motor insurance agents
- Health insurance agents
- Life insurance agents
- Composite agencies
- Insurance brokers
- Corporate agents
- Point of sale networks
- Agencies running sub-agents under their own code
- Group and employee benefit advisors
- Fire and marine specialists
- Crop and rural insurance agents
- Motor dealer insurance desks
- Bancassurance teams
- Third party administrators
- Multi-branch agency firms
The modules, and what each one covers.
Nothing here is a fixed package. Each module is built, left out or changed to match how your organisation already works.
The whole book in one list
Sorted by expiry date, across every insurer you place business with.
- Policies expiring this week
- Expiring this month
- Already lapsed
- Renewed and pending renewal
- By product
- By insurer
- By customer
- By executive
- Break-in cases
- Policies moved elsewhere
The customer record
- Name and contact details
- Family members covered
- Vehicles owned
- Shops, warehouses and premises
- All policies held with you
- Policies held elsewhere
- Claim history
- Documents
- Preferred language and channel
- Who introduced them
One customer, one file. A motor customer today is a health and shop customer next year, and the record already holds the family.
What a policy record carries
- Policy number and insurer
- Product and plan
- Risk start and expiry date
- Sum insured or insured declared value (IDV)
- Premium and taxes
- Payment mode and date
- Nominee
- Add-on covers
- Endorsements
- Policy PDF
Motor policies
- Vehicle make, model and variant
- Registration number and chassis
- Year of manufacture
- Own damage and third party cover
- IDV
- No-claim bonus carried forward
- Add-ons such as zero depreciation and roadside cover
- Previous insurer and policy
- Claim in the expiring year
- Break-in inspection status
A lapsed motor policy costs the customer the no-claim bonus, and usually costs the agency the customer. The reminder is the core of this module.
Health and group policies
- Members covered and their ages
- Sum insured and top-up
- Pre-existing conditions declared
- Waiting periods
- Room rent conditions
- Corporate group policy
- Member addition and deletion
- Employee list versions
- Renewal loading
- Portability cases
Shop, fire and marine
- Premises and stock covered
- Sum insured and basis of valuation
- Perils covered
- Business interruption
- Transit and marine cover
- Declaration policies
- Bank or financier interest noted
- Survey requirement
- Renewal documents
The renewal calendar
- Expiry date
- Early reminder
- Quote refresh
- Customer call
- Payment
- Issuance
- Delivery
- Next year’s reminder
The daily call list
A list your executive can finish before lunch.
- Calls due today
- Customer and policy in one line
- Last year’s premium
- Claim in the expiring year
- Call outcome
- Promised to pay date
- Not reachable
- Asked for a quote
- Moved to another agent
- Reason for loss
Quotes across insurers
Logging into three portals and retyping vehicle details is slow work, and the showroom may sell its own policy first.
- Details entered once
- Premium from each insurer added beside it
- Add-on comparison
- Discount applied
- Comparison sheet with your branding
- Sent on WhatsApp or email
- Quote validity
- Customer choice recorded
- Quotes that did not convert
Premiums are pulled from the insurer portals by whoever quotes them. Where an insurer offers no route in, the figure is typed, and the system stores it rather than calculating it.
New business
- Enquiry
- Requirement
- Quotes
- Comparison
- Documents
- Proposal
- Payment
- Issuance
Issuance and the insurer portals
The policy is still issued on the insurer’s own portal, by your team, with their login.
Connecting to an insurer’s system needs their permission and their interface, and most agencies are not given one. Assume the portal work stays manual unless that insurer says otherwise.
Endorsements
- Change of address
- Vehicle transfer
- Nominee change
- Member addition or deletion
- Sum insured revision
- Financier or hypothecation change
- Correction of details
- Documents submitted
- Endorsement status
- Copy filed against the policy
Claims
The customer calls the agency and not the insurer, so a claim log lets the agency say what went where.
- Claim intimation and number
- Policy and customer
- Date and nature of loss
- Insurer and third party administrator (TPA)
- Surveyor or investigator
- Documents asked for and sent
- Current stage
- Next follow-up date
- Approved and settled amount
- Rejection and the reason given
Motor claims
- Accident details and photographs
- Garage and estimate
- Cashless or reimbursement
- Surveyor visit
- Approval on the estimate
- Supplementary approval
- Salvage and depreciation deductions
- Delivery of the vehicle
- Settlement amount
- Effect on next year’s no-claim bonus
Health claims
A hospital may call late at night about a cashless approval, so the file has to be on a phone.
- Pre-authorisation request
- Hospital and treating doctor
- TPA reference number
- Approval, query or denial
- Documents sent against each query
- Discharge summary and bills
- Reimbursement submission
- Deductions made
- Settlement
- Escalation history
The decision on a claim belongs to the insurer or the TPA. What your file keeps is the trail of what was sent and when, which is what an escalation needs.
Documents
- Proposal forms
- Previous year policy
- Registration certificate and driving licence
- National ID and tax ID
- Medical reports
- Invoice and delivery note for new vehicles
- Bank details
- Claim documents
- Signed mandates
- Documents still awaited from the customer
Commission and payouts
- Business placed by insurer and product
- Expected payout against each policy
- Payout statement received
- Matched and unmatched entries
- Short payments
- Payouts received late
- Recovery on cancelled policies
- Sub-agent share
- Executive incentive
- Income by product and insurer
What an intermediary may be paid, and by whom, is set by the insurer and the rules it works under. The system records the arrangement you already have, and does not advise on it.
Reconciling a payout statement
A short payment on one motor product looks small until a year of it is added up.
- Statement received
- Upload
- Match against policies
- Differences listed
- Query to the insurer
- Correction or write-off
Sub-agents and point of sale staff
- Sub-agent record
- Business sourced by each
- Policies and premium
- Payout share agreed
- Amount due and paid
- Statements
- Training and licence status
- Renewal book held by each
- Performance
Customer portal
- All policies in one place
- Download policy copies
- Renewal due dates
- Pay renewal premium
- Request a quote
- Intimate a claim
- Track claim status
- Upload documents
- Add a vehicle or family member
- Contact your executive
Reminders and messages
- Renewal reminder at intervals you set
- Payment link
- Policy copy on issuance
- Claim status updates
- Document requests
- Birthday and greeting messages
- Health check-up reminders
- Feedback after a claim
Insurance wording is read closely, by the insurer and by the messaging provider both. A renewal reminder carrying a premium figure usually has to become a link instead.
Leads and cross-sell
- Enquiries from the website
- Walk-ins and phone calls
- Referrals from existing customers
- Dealer and garage referrals
- Motor customers with no health cover
- Families with one vehicle insured out of three
- Shop owners with no fire cover
- Follow-up list
- Conversion
- Lost enquiries
Corporate and group clients
- Company record
- Group policies held
- Employee lists
- Mid-term additions
- Claims by employee
- Utilisation of the group cover
- Renewal negotiation history
- Broker or insurer relationship
- Service level agreed
- Documents
Your team
- Executive records
- Customers allotted
- Renewal book held
- Calls made
- Renewals closed
- New business written
- Claims handled
- Targets
- Incentive working
- Handover when somebody leaves
What the owner opens
- Renewals due this month
- Renewals closed and lost
- New policies written
- Premium placed by insurer
- Commission earned and received
- Commission still pending
- Claims open by stage
- Claims rejected
- Customers with only one policy
- Executive performance
- Product mix
- Branch performance
Who sees what
- Agency owner
- Branch manager
- Renewal executive
- New business executive
- Claims executive
- Tele-caller
- Accounts
- Sub-agent
- Customer
More than one branch
- Branch-wise policies
- Renewal book by branch
- Premium and commission
- Claims
- Executive performance
- Expenses
- Customers shared between branches
What it connects to
- Payment gateways and links
- WhatsApp and SMS providers
- Accounting software
- Website enquiry forms
- Document storage
- Calling systems
- Vehicle detail lookups
- Insurer and TPA portals where they permit it
Insurer and TPA connections are the exception rather than the rule. We check what each one permits for an agency of your kind before anything goes into a plan.
One connected workflow, end to end.
Every stage below can sit in one system, so nobody re-enters what the last stage already captured.
- Enquiry
- Requirement
- Quotes
- Comparison
- Proposal
- Payment
- Issuance
- Delivery
- Service
- Claim
- Reminder
- Renewal
You do not have to replace everything at once.
Each phase is usable on its own, so the system earns its place before the next part is built.
- 1
The book and the renewals
Customers, policies, expiry dates, the daily call list and reminders. Everything else depends on the renewal book being complete.
- 2
Quotes and new business
Requirement capture, comparison sheets across insurers, proposal documents and the record of what the customer chose.
- 3
Claims
Intimation, TPA and surveyor follow-up, documents sent, stage tracking and the escalation trail behind each file.
- 4
Payouts and the portal
Commission expected against received, sub-agent shares, the customer portal, and the handful of reports the owner opens.
How a build actually runs.
- 01
Sit through a renewal week
We watch how the expiry list is built today, and how many places it has to be built from.
- 02
Map
Products, insurers, customers, executives, payout arrangements and every document a claim needs.
- 03
Design
The call list first. If that screen is wrong, nothing else on the page matters.
- 04
Build
The policy book, renewals and reminders, then claims, then the payout reconciliation.
- 05
Load the book
Existing policies come in from insurer statements and spreadsheets, with the duplicates cleaned as they arrive.
- 06
Deploy
Go-live with your executives working the real call list, and the old sheet kept for one cycle.
- 07
Extend
The customer portal, cross-sell lists and sub-agent accounts, once renewals run smoothly.
What you bring, and when.
The build moves at the speed of the answers. These are the things we ask for, in the order we ask.
- 01
Policy register and renewal lists
Bring the sheet where you track policies, a recent renewal list and a few insurer quotes. Add commission statements. They show how the book runs today.
- 02
A servicing lead and an accounts person
Servicing staff know customers and calls. Accounts know commissions. The agency principal decides whose rule stands.
- 03
Commission rates and call routines
Commission rates by insurer and the order of renewal calls are decided during development. The servicing team reviews screens with real customers. Early feedback matters.
- 04
Customer data and insurer portal access
Customer and policy data moves in after cleaning. Credentials for insurer portals stay with you. The principal accepts the starting list.
Systems we can put together for you.
- Insurance agency management software
- Policy and renewal tracking systems
- Insurance CRM
- Quote comparison tools
- Claims tracking systems
- Commission and payout reconciliation software
- Sub-agent and point of sale portals
- Customer self-service portals
- Customer mobile applications
- Group and corporate policy management
- Lead and cross-sell systems
- Document management for policy files
- Agency dashboards
- Multi-tenant insurance platforms
Questions owners ask before starting.
What is custom insurance agency software?
Everything is designed around one agency’s book: the policies you hold, the insurers you place with, your payout arrangements and the way your team chases renewals.
Will it issue policies for us?
No. Issuance stays on the insurer’s portal with your own login, because almost no insurer opens that to an agency. The system holds everything around it.
Can we see every policy by expiry date in one list?
Yes. One list across insurers and products, sorted by expiry date.
Can renewal reminders go out on WhatsApp?
Yes, through an approved provider. What the message may say is set by their template rules, and insurance wording is checked more closely than most.
Can it tell us if an insurer has short-paid us?
Yes. Expected payout is held against each policy, the statement is matched to it, and the differences are listed instead of being noticed a year later.
How are claims tracked for customers?
Intimation, TPA reference, documents sent, queries raised, the stage today and the next follow-up date all sit against the customer’s file.
Can sub-agents have their own login?
Yes. Each sub-agent sees the business they sourced, their share and their statement, and nothing belonging to anybody else.
Can customers download their own policy copies?
Yes, through a portal. It also saves your staff from fetching last year’s copy by hand.
Is old policy data imported?
Usually. Insurer statements and Excel sheets can be imported, though matching one customer across four spellings of his name is real work.
Can this be built for a broker with several branches?
Yes. Branch-wise books, shared customers and consolidated reporting are part of the design when several offices are involved.
What will it not do?
It will not decide a claim, set a payout rate, or advise you on what you are permitted to charge. Those belong to the insurer and to your own advice.
How we work with this trade.
Build an agency system that never misses an expiry date.
The renewal you forgot is the customer you lose, and usually his family and his shop with him.
Whether you need a renewal book across insurers, a claims desk, a payout reconciliation tool or a customer portal, tell us how your agency works today. The renewal book comes first. Everything else can stand behind it.
Tell us how your insurance agencies runs today.
We will tell you what can be digitised, what can be connected, what is worth automating, and what you should leave alone.
What happens after you share your requirements
- A senior engineer reads your answers. Nobody phones first.
- Within one business day you get a written note: what we understood, what we would start with, and the questions we still have.
- If it fits, a proposal follows with the order of work, what we need from you and what you receive at each step.
- No call is booked and nothing is paid until you have read the note. Your details stay with us.
Start with your requirements
Seven short steps that tell us what you need. A senior engineer reads them before anyone gets in touch.
Share your requirements