Business solutions for NBFCs
Explore software for work such as “Dealer and DSA partner programmes”. Review each business function below, including when it fits and what to check before implementation.
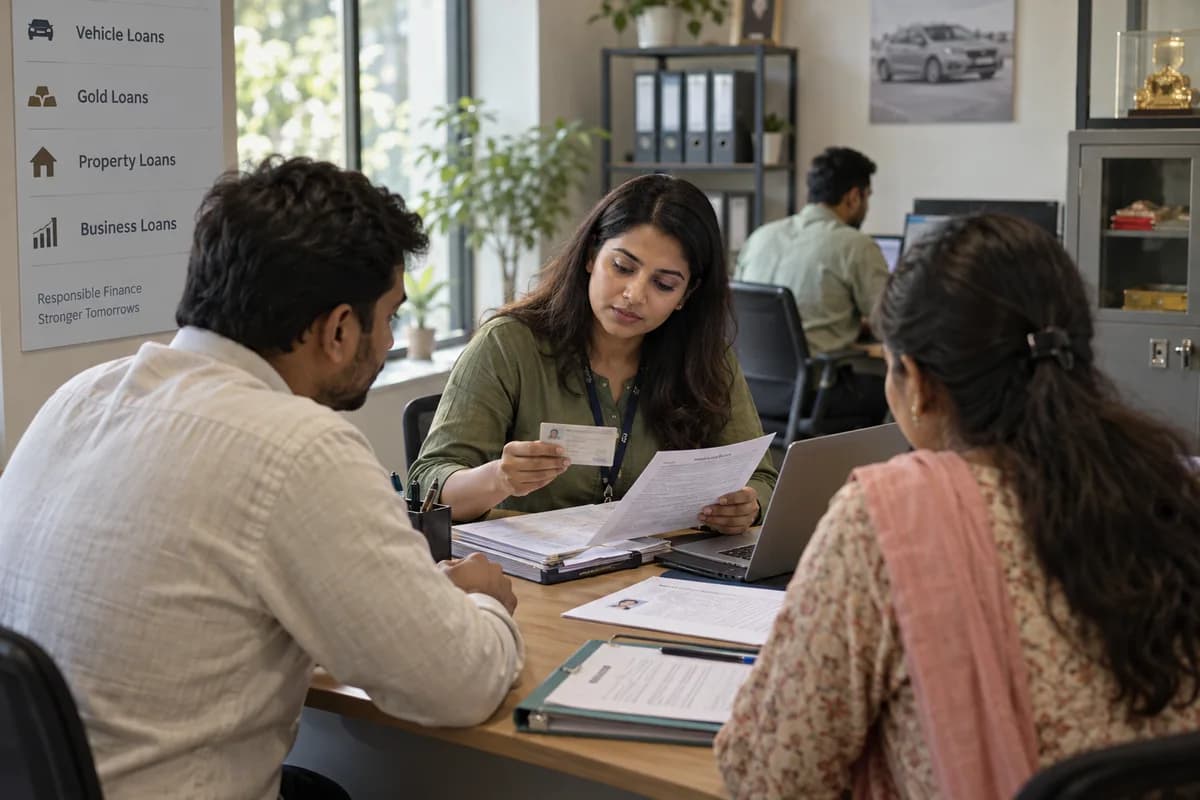
How the business operates.
A small NBFC may run several products at once: used vehicle loans, gold loans, loans against property and unsecured business loans. Each has its own documents, approval levels and collection rhythm. A gold loan hinges on purity and net weight, while a property loan waits on a legal opinion and title search.
The records that hold the operation together.
- Enquiries and leads. Log every enquiry with its source and a follow-up date. Report on which enquiries became applications.
- Borrower and group records. Keep one record per borrower with loans, guarantors and interaction history. For group lending, members sit inside their group so group totals and member dues agree.
- Loan applications and ID documents. Track a checklist per loan product. Store scanned ID papers, tax documents, bank statements and agreements against the application.
- Appraisal and credit notes. Record income, existing loans, credit history and a risk note. The approver reviews the same page as the officer.
- Sanction approvals and committee resolutions. Set approval levels by amount or product. Disbursement waits for the required sign-off, and the log shows who approved and when. Keep the member, the surety and the committee resolution against each loan, with the total loans backed by each surety. Share capital and deposits stay in your own books.
- Disbursement register. Record each release with date, amount, mode and bank reference. Track part disbursements against the sanctioned amount.
- Instalment schedules and several loan products. Build schedules from principal, rate, tenure and frequency, weekly or monthly, on a flat or reducing balance method. The borrower’s copy and your ledger show the same instalments. Set separate products with their own interest method, fees, tenure and approval levels, and read them together in one overdue and disbursement report. It is not a regulatory reporting system.
- Collection app for field agents and centre meetings. Collectors record receipts against the borrower from a phone browser. Due and received amounts appear together, with the collector’s name and date. Group loans are shown by centre and group, with a receipt per member and absentees marked at the meeting. Weekly or fortnightly schedules and group totals come from the member lines.
Operational bottlenecks to check
The loan book lives in three places
The loan system, Excel and the books each hold a different figure for outstanding principal. Month end starts with matching them line by line, before anyone can quote an overdue-loan figure.
Field receipts reach the office late
Collectors bring cash and handwritten receipt books back at night, and the loan account updates the next day. Borrowers who already paid still get reminder calls and a bruised relationship.
Buckets are rebuilt by filter
DPD is worked out from an export, and visits are assigned from that list some days later. Accounts one instalment behind wait while the larger overdue files get attention.
Approvals leave no trail
A sanction agreed on a phone call shows no name or time on the file when the auditor asks who approved the exception to the loan-to-value limit. The question goes round.
Collateral is tracked in a ledger book
Gold packets, registration certificates and title deeds sit in a safe with a handwritten register. Release on closure depends on someone remembering which packet, which seal number and which borrower.
Follow the work across teams.
This is a planning flow. Confirm the steps, owners and approval rules against your actual operation.
Roles and responsibility boundaries.
Reports your managers need.
- Demand versus collection for the day, week or month, by collector and by branch
- Overdue ageing by bucket, with the borrower list behind each figure
- Disbursements by product, officer and month
- Group-wise outstanding and member-wise repayment history
- Applications pending sanction and the documents each one is missing
- Commission earned on recoveries, worked out from actual receipts
- Loans closing this month and collateral due for release
Connections to scope
- Accounting export
- SMS
- Payment links and gateways
Confirm data access, record ownership and the exchange method for each connection. Inclusion here does not mean every connection is available in a standard package.
Setup decisions and adoption risks.
Use these requirements to plan phases, data migration and user training. Agree the release sequence after reviewing your current systems.
Limitations to settle before implementation
- Large banks and finance companies that need a core banking system with credit bureau and regulator feeds built in
- A lender with a handful of loans a month, where a well-kept spreadsheet is still enough
- Anyone looking for software that makes lending decisions automatically
Modules to consider first.
These functions connect to the operating model above. Confirm each one against the work your business actually runs.
Choose the operation you want to improve.
Use these activities to explain your scope. Your business does not need every function in the directory.
- Dealer and DSA partner programmes
- Document collection and file-chasing on WhatsApp
- Telecalling scripts and call back discipline
- Partner onboarding and training
- Lead quality filters before the call
Explore the business functions.
Production, stock, fleet and recurring billing functions apply only where your business runs those activities. Read the suitability conditions on each page.
Platform
Sales and Distribution
Human Resources
CRM
Finance & Accounting
Start with the problem your team can describe.
Bring a sample record and show where information is copied, missed or waiting for approval. Scope the first useful change from there.
What happens after you share your requirements
- We review your brief and the systems you already use.
- We clarify the workflow, missing information and the work to consider first.
- The proposed scope sets out the deliverables, responsibilities and dependencies.
- Review the scope and commercial terms before deciding whether to proceed.
Start with your requirements
Describe your current process, the people involved and the change you need. Start with the details you know; we can clarify the rest together.
Share your requirements