Commission and Incentives for NBFCs
Calculate incentive amounts from approved sales or collection rules.
Does this function belong in your operation?
Use when compensation depends on recorded sales, collections or other agreed outcomes.
A commission period is ready for review.
Loan agents and branch staff are paid on disbursals that meet the set conditions. A loan closed early or that falls into default can reverse part of the payout. Totals are shown for each agent.
Bring the records the workflow depends on.
- Eligible transactions
- Commission rules and dates
- Participant assignments
Outputs to check
- Transaction-level incentive calculation
- Adjustment and approval statement
- Payout handoff record
Follow the commission and incentives workflow.
Use this sequence to compare your current process with the proposed module. Agree the owner, permission and exception at each step.
Who uses the module, and who approves?
Keep responsibilities distinct even when one person holds more than one role.
Decide how exceptions are handled.
These business rules belong in configuration and testing. A normal transaction alone does not demonstrate that the workflow is ready.
Can this work independently?
Calculation needs eligible sales or collection records and effective-dated rules. It can run from imports without payroll, but payroll or accounts performs the payment. Returns, credits and reversals must feed the calculation so a booked sale is not rewarded twice or retained after reversal.
Systems and records it connects with
- Invoice management: Issued invoice references, line amounts and outstanding balances.
- Receipts management: Recorded customer payments and invoice allocations.
- Collections and follow-up: Due balances, payment promises and follow-up outcomes.
- Payroll: Approved pay inputs, deduction calculations and payment instructions.
Configure, test and introduce the workflow.
- You describe how each role is paid, on paper or aloud. You get a written note of each rule in plain language to confirm. Plain words are enough.
- Old and new rates are entered with the dates they apply from. You get a screen to check a past month against what was paid. Past months are good tests. Statements are produced for a few people from last month’s bills. They read them, and you hear what does not match. People check their own.
- You decide what pulls a commission back and when. The rules are tested with returned orders and bounced cheques. Edge cases come out here. The accounts team prepares payouts from the statements and marks them. Staff are shown how to read their own statement. Questions drop quickly.
Check the result before rollout.
Apply these checks to a sample from the agreed workflow, then repeat with an exception. Keep the expected result beside the test record.
- Calculations trace to qualifying transactions.
- Returns follow the agreed reversal rule.
- Rule changes use the correct effective date.
How the business operates.
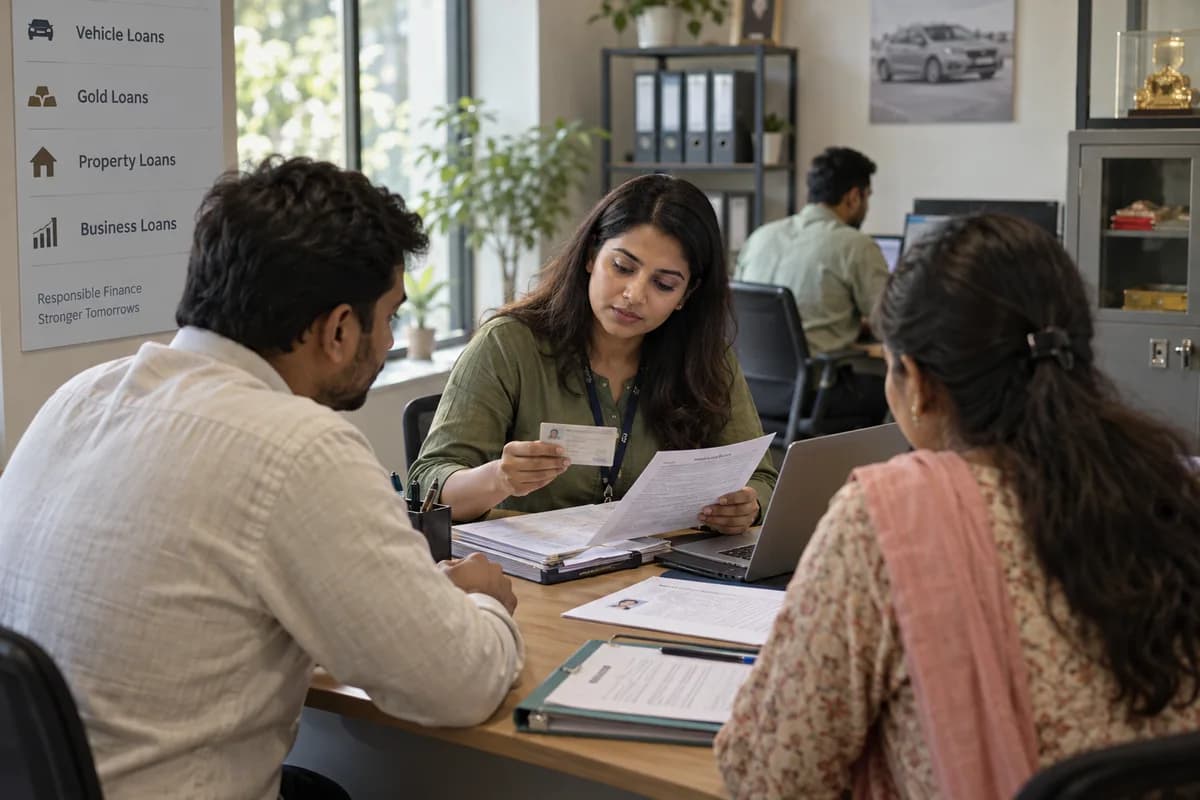
A small NBFC may run several products at once: used vehicle loans, gold loans, loans against property and unsecured business loans. Each has its own documents, approval levels and collection rhythm. A gold loan hinges on purity and net weight, while a property loan waits on a legal opinion and title search.
The records that hold the operation together.
- Enquiries and leads. Log every enquiry with its source and a follow-up date. Report on which enquiries became applications.
- Borrower and group records. Keep one record per borrower with loans, guarantors and interaction history. For group lending, members sit inside their group so group totals and member dues agree.
- Loan applications and ID documents. Track a checklist per loan product. Store scanned ID papers, tax documents, bank statements and agreements against the application.
- Appraisal and credit notes. Record income, existing loans, credit history and a risk note. The approver reviews the same page as the officer.
Operational bottlenecks to check
The loan book lives in three places
The loan system, Excel and the books each hold a different figure for outstanding principal. Month end starts with matching them line by line, before anyone can quote an overdue-loan figure.
Field receipts reach the office late
Collectors bring cash and handwritten receipt books back at night, and the loan account updates the next day. Borrowers who already paid still get reminder calls and a bruised relationship.
How work flows across this business
This module sits within a wider operating process. Use the sequence to identify the other teams and records affected by a change.
1. Enquiry and application
Log the enquiry with its source, such as a walk-in, an agent or a referral. When the borrower applies, attach ID papers, income proof and guarantor details to the application.
2. Appraisal and sanction
The loan officer records the appraisal, credit history and collateral. The file goes to the approver for that loan size, and each approval carries a name and a time.
3. Disbursement
Record the release with date, mode and reference. The instalment schedule is generated from the rate, the tenure and the start date.
4. Collection
Collectors open their route or groups and see who is due. Each receipt is entered against the borrower with the collector’s name, and the office sees it the same day.
5. Overdue follow-up
Accounts move into overdue buckets when an instalment is missed. Reminders go out, visits are assigned, and promises to pay are recorded on the loan.
6. Closure and renewal
The loan closes when the last instalment is received, and collateral is marked for release. Eligible borrowers can be offered a renewal or top-up from the same record.
Industry reports to connect with
- Demand versus collection for the day, week or month, by collector and by branch
- Overdue ageing by bucket, with the borrower list behind each figure
- Disbursements by product, officer and month
- Group-wise outstanding and member-wise repayment history
Questions before implementation.
When should nbfcs consider commission and incentives?
Use when compensation depends on recorded sales, collections or other agreed outcomes. A commission period is ready for review.
What should we bring to the requirements discussion?
Bring anonymised examples of Eligible transactions; Commission rules and dates; Participant assignments. Show who creates, checks and changes each record. Use only records from an activity that meets the suitability conditions above.
Does this replace our existing business software?
The starting point is your current system and the gap you need to close. Calculate incentive amounts from approved sales or collection rules. Configuration, a connected module or a custom build are evaluated against that gap before a replacement is proposed.
What is outside this module?
Employment terms, tax treatment and payout approval remain with your authorised team.
How are scope, price and rollout decided?
The proposal follows a review of your records, user roles, branches and existing software. Data migration, connections, training and support are scoped separately where needed. Calculations trace to qualifying transactions. Use this check when reviewing the first working version.
Related functions for nbfcs.
Discuss commission and incentives for your business.
Tell us which workflow needs attention and which systems your team uses. The next step is a requirements discussion and a written scope.
What happens after you share your requirements
- We review your brief and the systems you already use.
- We clarify the workflow, missing information and the work to consider first.
- The proposed scope sets out the deliverables, responsibilities and dependencies.
- Review the scope and commercial terms before deciding whether to proceed.
Start with your requirements
Describe your current process, the people involved and the change you need. Start with the details you know; we can clarify the rest together.
Share your requirements