Multi-Currency Support for Payment service providers
Keep original-currency amounts beside accounting-currency values.
Does this function belong in your operation?
Use when invoices, purchases or settlements use multiple currencies.
A transaction uses another currency.
Card volume arrives in several currencies and settles in the merchant’s payout currency. The exchange rate used and the fee on the conversion are shown for each batch. Finance sees both amounts.
Bring the records the workflow depends on.
- Currencies
- Rate sources and dates
- Settlement rules
Outputs to check
- Original and base-currency values
- Exchange-rate application history
- Settlement-difference record
Follow the multi-currency support workflow.
Use this sequence to compare your current process with the proposed module. Agree the owner, permission and exception at each step.
Who uses the module, and who approves?
Keep responsibilities distinct even when one person holds more than one role.
Decide how exceptions are handled.
These business rules belong in configuration and testing. A normal transaction alone does not demonstrate that the workflow is ready.
Can this work independently?
Currency handling depends on the transaction and accounting records it values. It is not a standalone ledger or payment service. Rates can be supplied through an approved manual table or supported feed, with the effective date and accounting policy recorded.
Systems and records it connects with
- Invoice management: Issued invoice references, line amounts and outstanding balances.
- Proforma invoice: Provisional supply amounts and related advance requests.
- Bank reconciliation: Cleared, unmatched and reversed bank transactions.
- Finance and accounting reporting: Ledger-based period totals and reconciliation outputs.
Configure, test and introduce the workflow.
- List your billing currencies and buyers. The setup for every customer is laid out on paper.
- Your accountant chooses where rates come from and who enters them. Rates held by date then appear for trial. Provide foreign invoices and their remittances. A trial run shows exchange differences and bank charges per bill.
- Export staff and accounts practise on sample documents. Notes from the session return as a checklist. New foreign invoices are raised in the system. The accountant reviews the first reconciliation with the team.
Check the result before rollout.
Apply these checks to a sample from the agreed workflow, then repeat with an exception. Keep the expected result beside the test record.
- Original amounts remain visible.
- Conversions retain rates and dates.
- Differences reconcile with entries.
How the business operates.
A payment business keeps two kinds of record. One is the transaction stream from your gateway or acquiring partner. The other is the context around it: who the merchant is, which merchant discount rate applies, what was paid out, what sits in reserve and what is disputed.
The records that hold the operation together.
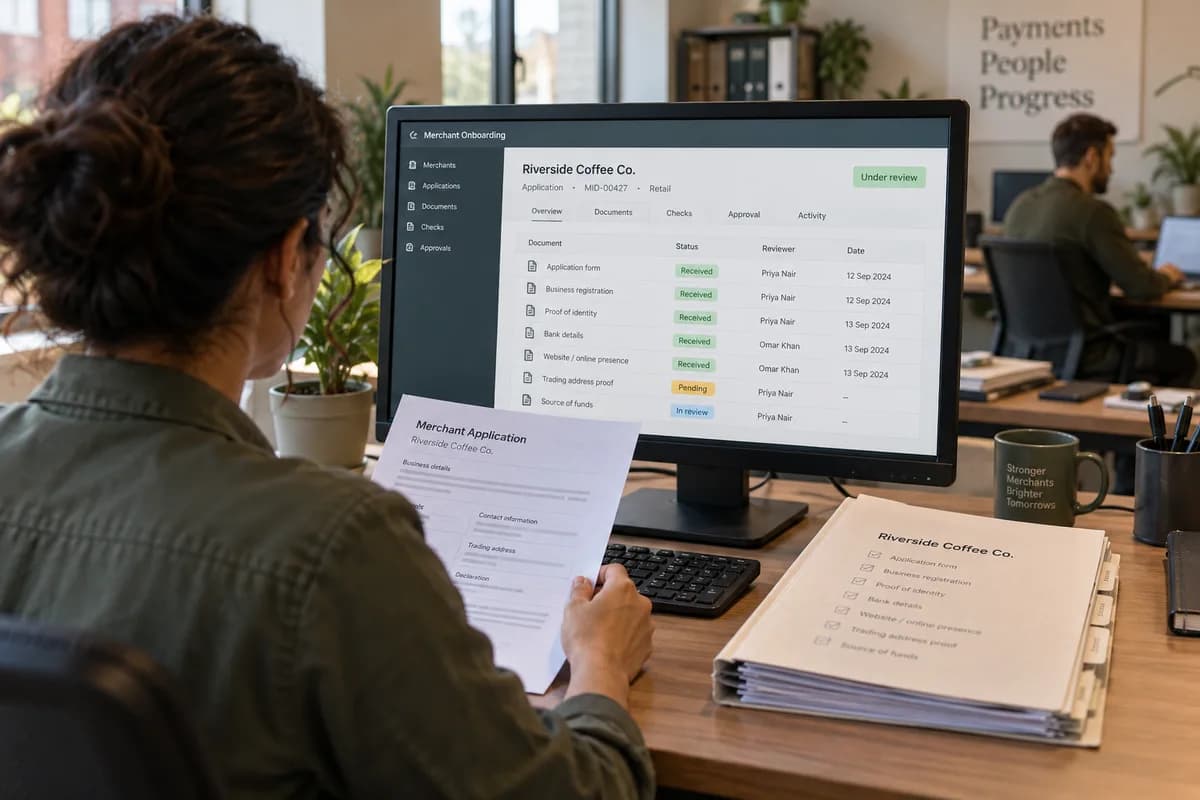
- Merchant application and KYC file. Open one file per merchant with the application, ownership papers, director identity documents for know-your-customer checks, bank proof and website review. A checklist shows which paper is missing and who is chasing it.
- Screening and risk review log. Record each sanctions and adverse-media check with its result, reviewer and date. Assign the merchant category code and a risk tier, and keep the reasoning for an approval or a decline.
- Contracts and rate cards. Store the signed merchant agreement beside its pricing: discount rate, per-transaction fee, scheme pass-through and payout terms by payment mode, each with an effective date.
- Capture and transaction file import. Load the capture, refund and fee files from your gateway or acquirer in the layouts they send. Totals per merchant and per day are shown before any payout is built.
Operational bottlenecks to check
Onboarding stalls on one paper
One identity-check file is parked for a director’s address proof, but the team cannot count other files waiting for the same document. Merchants sign with a rival gateway.
Rate cards live in a spreadsheet
Someone keys the negotiated rate by hand. The payout then runs at the standard rate. Finance posts a reversal a fortnight later.
How work flows across this business
This module sits within a wider operating process. Use the sequence to identify the other teams and records affected by a change.
1. Application
A merchant applies through a form or a sales contact. The business type, expected volume, payment modes and website are captured, and an analyst is assigned.
2. KYC and screening
Papers are collected against a checklist. Ownership is mapped, names are screened, a category code and risk tier are set, and approval is recorded with its reasons.
3. Pricing and go-live
The signed agreement and rate card are attached with effective dates. Settlement account details are verified before the merchant is switched on in your gateway.
4. Capture and payout
Capture and fee files are imported each cycle. A batch is built net of fees, refunds and reserves, reviewed by an approver and passed to the bank process.
5. Reconciliation
Batches are matched with the sponsor bank statement and partner files. Breaks get a cause and an owner, and clear before the cycle is closed.
6. Disputes and support
Chargebacks, refunds and merchant queries are worked from one desk. Evidence is attached, deadlines watched, and outcomes posted to the next payout advice.
Industry reports to connect with
- Applications by stage, reviewer and missing document
- Merchants by risk tier, category code and payment mode
- Payout batches by cycle, with fees, refunds and reserves deducted
- Reconciliation breaks by cause, age and owner
Questions before implementation.
When should payment service providers consider multi-currency support?
Use when invoices, purchases or settlements use multiple currencies. A transaction uses another currency.
What should we bring to the requirements discussion?
Bring anonymised examples of Currencies; Rate sources and dates; Settlement rules. Show who creates, checks and changes each record. Use only records from an activity that meets the suitability conditions above.
Does this replace our existing business software?
The starting point is your current system and the gap you need to close. Keep original-currency amounts beside accounting-currency values. Configuration, a connected module or a custom build are evaluated against that gap before a replacement is proposed.
What is outside this module?
Finance advisers approve exchange-rate and revaluation policy.
How are scope, price and rollout decided?
The proposal follows a review of your records, user roles, branches and existing software. Data migration, connections, training and support are scoped separately where needed. Original amounts remain visible. Use this check when reviewing the first working version.
Related functions for payment service providers.
Discuss multi-currency support for your business.
Tell us which workflow needs attention and which systems your team uses. The next step is a requirements discussion and a written scope.
What happens after you share your requirements
- We review your brief and the systems you already use.
- We clarify the workflow, missing information and the work to consider first.
- The proposed scope sets out the deliverables, responsibilities and dependencies.
- Review the scope and commercial terms before deciding whether to proceed.
Start with your requirements
Describe your current process, the people involved and the change you need. Start with the details you know; we can clarify the rest together.
Share your requirements