Business solutions for Payment service providers
Explore software for work such as “UPI QR, soundbox and card machines for shops”. Review each business function below, including when it fits and what to check before implementation.
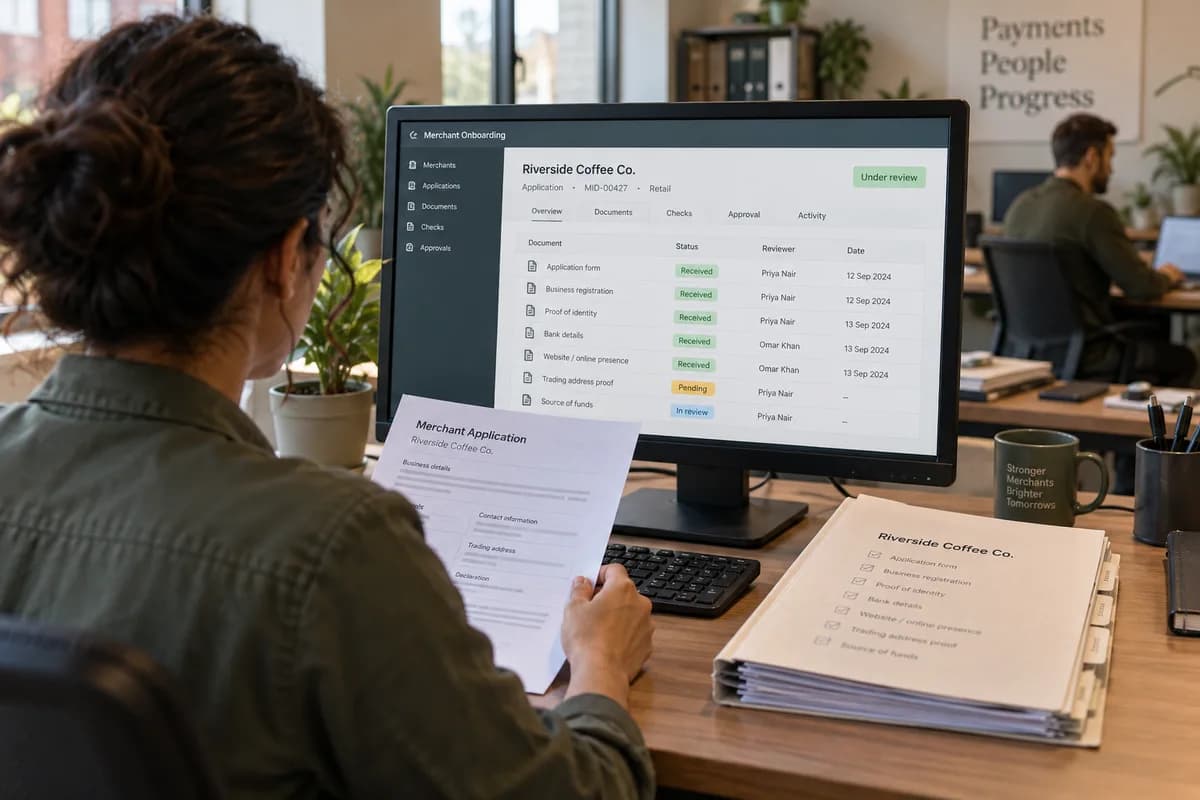
How the business operates.
A payment business keeps two kinds of record. One is the transaction stream from your gateway or acquiring partner. The other is the context around it: who the merchant is, which merchant discount rate applies, what was paid out, what sits in reserve and what is disputed.
The records that hold the operation together.
- Merchant application and KYC file. Open one file per merchant with the application, ownership papers, director identity documents for know-your-customer checks, bank proof and website review. A checklist shows which paper is missing and who is chasing it.
- Screening and risk review log. Record each sanctions and adverse-media check with its result, reviewer and date. Assign the merchant category code and a risk tier, and keep the reasoning for an approval or a decline.
- Contracts and rate cards. Store the signed merchant agreement beside its pricing: discount rate, per-transaction fee, scheme pass-through and payout terms by payment mode, each with an effective date.
- Capture and transaction file import. Load the capture, refund and fee files from your gateway or acquirer in the layouts they send. Totals per merchant and per day are shown before any payout is built.
- Settlement batches. Build each payout batch from imported captures less fees, refunds and reserve holds, and show the net per merchant. A named approver releases it, and the bank instruction stays in your banking process.
- Reserves and holds. Place a rolling reserve, a delayed payout or a hold on a merchant or a transaction. Record the reason, the approver and the release date, and see the effect on the next batch.
- Partner and bank reconciliation. Match capture files, payout batches and sponsor bank statement lines. Every unmatched line carries a cause, an assigned owner and a live status, and stays on the list until someone closes it.
- Refunds and adjustments. Raise a refund or a manual adjustment against a transaction or merchant, with approval by value. Fees returned or retained are shown on the merchant’s next advice.
Operational bottlenecks to check
Onboarding stalls on one paper
One identity-check file is parked for a director’s address proof, but the team cannot count other files waiting for the same document. Merchants sign with a rival gateway.
Rate cards live in a spreadsheet
Someone keys the negotiated rate by hand. The payout then runs at the standard rate. Finance posts a reversal a fortnight later.
Payouts disagree with the sponsor bank
The payout file and the bank statement differ by a handful of lines, and tracing them takes a working day. The reason is seldom written down.
Representment deadlines slip
Visa and Mastercard disputes arrive with a response date, while the proof of delivery sits in somebody’s inbox. Reply late and the case is lost.
Merchants ring to ask about money
Support cannot see reserve balances, refunds in flight or the next payout date. Each caller is passed to an accountant.
Follow the work across teams.
This is a planning flow. Confirm the steps, owners and approval rules against your actual operation.
Roles and responsibility boundaries.
Reports your managers need.
- Applications by stage, reviewer and missing document
- Merchants by risk tier, category code and payment mode
- Payout batches by cycle, with fees, refunds and reserves deducted
- Reconciliation breaks by cause, age and owner
- Reserves held and due for release by merchant
- Chargebacks by reason code, response date and outcome
- Refund and adjustment volume by merchant and approver
Connections to scope
- Payment gateway files and APIs
- Acquirer and sponsor bank statements
- Sanctions screening service
- SMS
- Accounting export
Confirm data access, record ownership and the exchange method for each connection. Inclusion here does not mean every connection is available in a standard package.
Setup decisions and adoption risks.
Use these requirements to plan phases, data migration and user training. Agree the release sequence after reviewing your current systems.
Limitations to settle before implementation
- A business that only accepts card payments through a hosted checkout has no merchant base to manage and needs only its own accounts.
- Banks that run deposits and loans will find Bank Management Software closer.
Modules to consider first.
These functions connect to the operating model above. Confirm each one against the work your business actually runs.
Choose the operation you want to improve.
Use these activities to explain your scope. Your business does not need every function in the directory.
- UPI QR, soundbox and card machines for shops
- Payment links for sellers who take orders on WhatsApp
- Recurring collections and mandates
- Payouts to vendors and sellers
- Reconciliation and settlement reports
- Embedded payments for platforms
- Cross-border collections
- Merchant onboarding and activation
Explore the business functions.
Production, stock, fleet and recurring billing functions apply only where your business runs those activities. Read the suitability conditions on each page.
Platform
Finance & Accounting
Bank Reconciliation
Match bank statement entries with the ledger.
View workflow and suitability →Client Portal
Give customers controlled access to account documents and requests.
View workflow and suitability →Multi-Currency Support
Keep original-currency amounts beside accounting-currency values.
View workflow and suitability →
Documents
Human Resources
Helpdesk
Start with the problem your team can describe.
Bring a sample record and show where information is copied, missed or waiting for approval. Scope the first useful change from there.
What happens after you share your requirements
- We review your brief and the systems you already use.
- We clarify the workflow, missing information and the work to consider first.
- The proposed scope sets out the deliverables, responsibilities and dependencies.
- Review the scope and commercial terms before deciding whether to proceed.
Start with your requirements
Describe your current process, the people involved and the change you need. Start with the details you know; we can clarify the rest together.
Share your requirements