In this guide 7 sections
Put every loan on one record, from KYC papers to the last EMI, and have field collectors enter each receipt against the borrower on their phone. Overdue buckets and the day’s collection against demand then read straight from those entries, instead of from one person’s private Excel sheet. Nothing waits for one laptop.
The EMI Register Only One Person Understands
In many small lending offices the loan book is an Excel file on the accountant’s laptop, with a row per borrower and a column per month. Colour codes mark who has paid.
It works until that person is away. Then nobody else can say whether a borrower paid last Tuesday, and the collectors guess from memory while the owner waits for answers.
Before you look at any loan software, write down what the sheet tracks: principal, rate, tenure, EMI frequency, collector and running balance. That list becomes your loan record. Wherever the sheet handles something badly, the new system must be stricter, and part payments, which sheets absorb by overwriting the old figure, usually top that list.
Field Cash on the Same Day’s Record
The evening handover is the risky moment. A collector arrives with cash and a notebook, and if the total is short, nothing ties any amount to a borrower, a collector and a date.
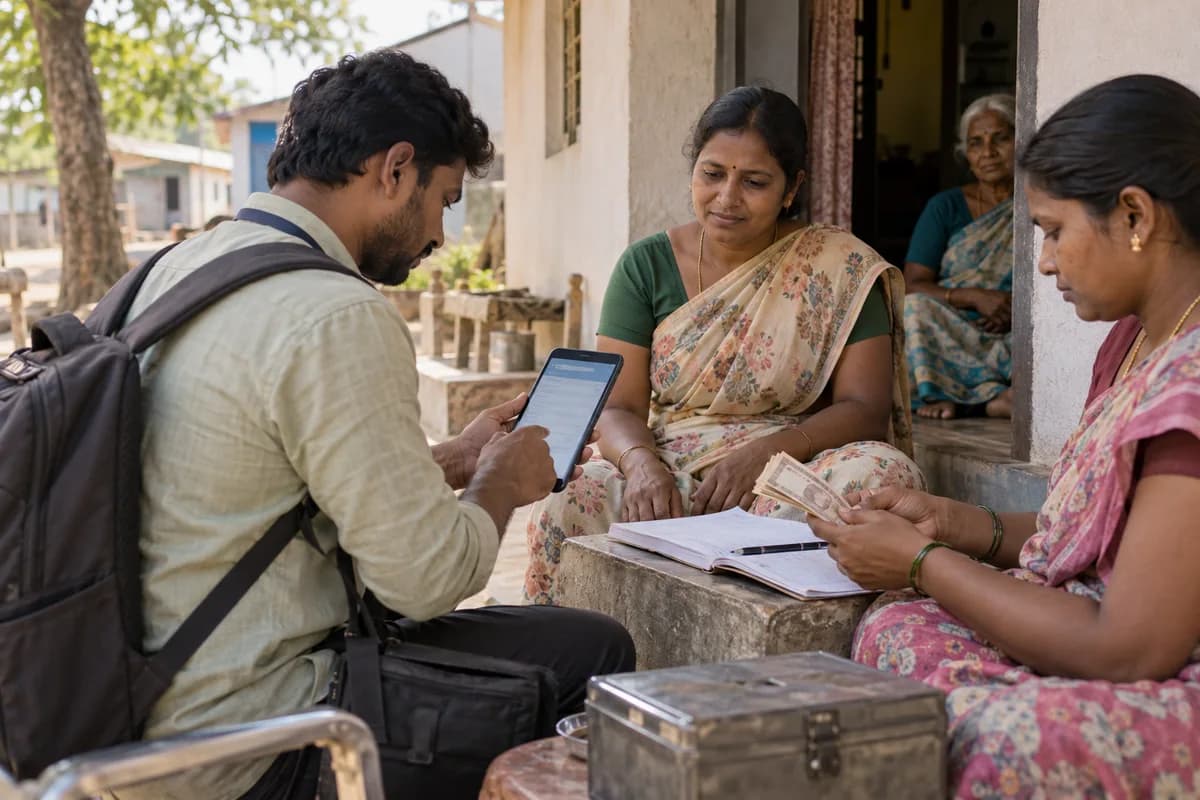
A collection agent app moves the entry to the borrower’s door, so the collector sees who is due and enters each receipt as the money is counted. The route opens in a phone browser. The office sees every receipt that afternoon.
One rule matters more than the software. A collector must not be able to edit a receipt once it is entered, because a correction made quietly is exactly how a short total gets hidden. Each receipt carries these fields.
- Loan number and borrower name
- Amount, mode and date of payment
- Collector’s name, recorded without anyone typing it
- Any promise to pay or part payment noted on the loan
SHG and Group Loans in One Record
Group lending strains spreadsheets faster than individual loans, because each Self Help Group gets its own sheet and each member a row copied into a second file. Within a few months the member totals stop adding up to the group total, and the meeting ends with two people arguing over arithmetic.
Software must hold members inside groups. The group’s collection is recorded member by member, so the group outstanding and each member’s dues come from the same entries rather than from two people’s sums.
If you arrange bank loans for SHGs and earn commission on recoveries, work out that commission from the actual receipts as well.
Overdue Buckets and Reminders
Ask a small lender how much is overdue past 60 days and the answer usually takes an afternoon of filtering and pivot tables. The list is not wrong. It is just late.
Once receipts go in daily, accounts sort into current, 1 to 30, 31 to 60, 61 to 90 and 90-plus day buckets, and due-date reminders go out by SMS. Overdue accounts are assigned for a visit, and each promise to pay stays on the loan where the next collector can read it.
Sanction approvals by loan size, stamped with the approver’s name and the time, belong in the same place, so a large loan never rests on a verbal yes.
When a Well-Kept Spreadsheet Is Still Enough
If you run a few dozen loans and one trusted person handles every receipt, a careful Excel file with locked formulas can serve you for a while. Software earns its place later. That is when money starts passing through several hands in the field and the notebook becomes the only record of a visit.
The Loan Management System is built for microfinance organisations, SHG lenders, gold loan businesses and co-operative credit societies, where one office supervises many collectors and many small loans. It is not a core banking system for large NBFCs, and it does not pull bureau reports or file regulatory returns on your behalf.
When you move, running loans and past receipts are imported from your sheets, and every opening balance is agreed with you line by line before go-live.
Loan book migration checklist
A single-page checklist for moving a loan book off Excel, listing the fields each loan record needs and how to agree opening balances for running loans. Receipt fields and overdue buckets follow.
Open a blank worksheet to printQuestions owners ask
Can a collector change a receipt after entering it?
Not if it is set up well. Collectors can be allowed to enter receipts but not edit them, and a correction comes from someone with that permission, with the log keeping both figures. Read that log first.
Will loan management software make my business RBI compliant?
No, because compliance comes from how you lend and collect, and the RBI’s microfinance framework covers pricing, the fair practices code and recovery of overdue loans. The software gives your auditor a dated, named record of every application, approval, disbursement and receipt, which is evidence of process, not a certificate. Ask your CA to confirm the current RBI rules, because they are revised from time to time and this guide cannot track each change.
Can the system handle part payments on an EMI?
Yes, it can. A part payment is entered like any receipt, with its date, amount and collector, and the remaining balance is worked out from the entries instead of typed in. The sheet habit of overwriting stops.
Sources
- RBI FAQs on the Regulatory Framework for Microfinance Loans (updated January 2025) — verified 20 Sept 2026