Field Collection App for Loan Collectors
A collector opens the day’s route on a phone, sees who is due and records each receipt at the door. Cash handed over at the office is listed against those receipts. The desk sees the day as it happens.
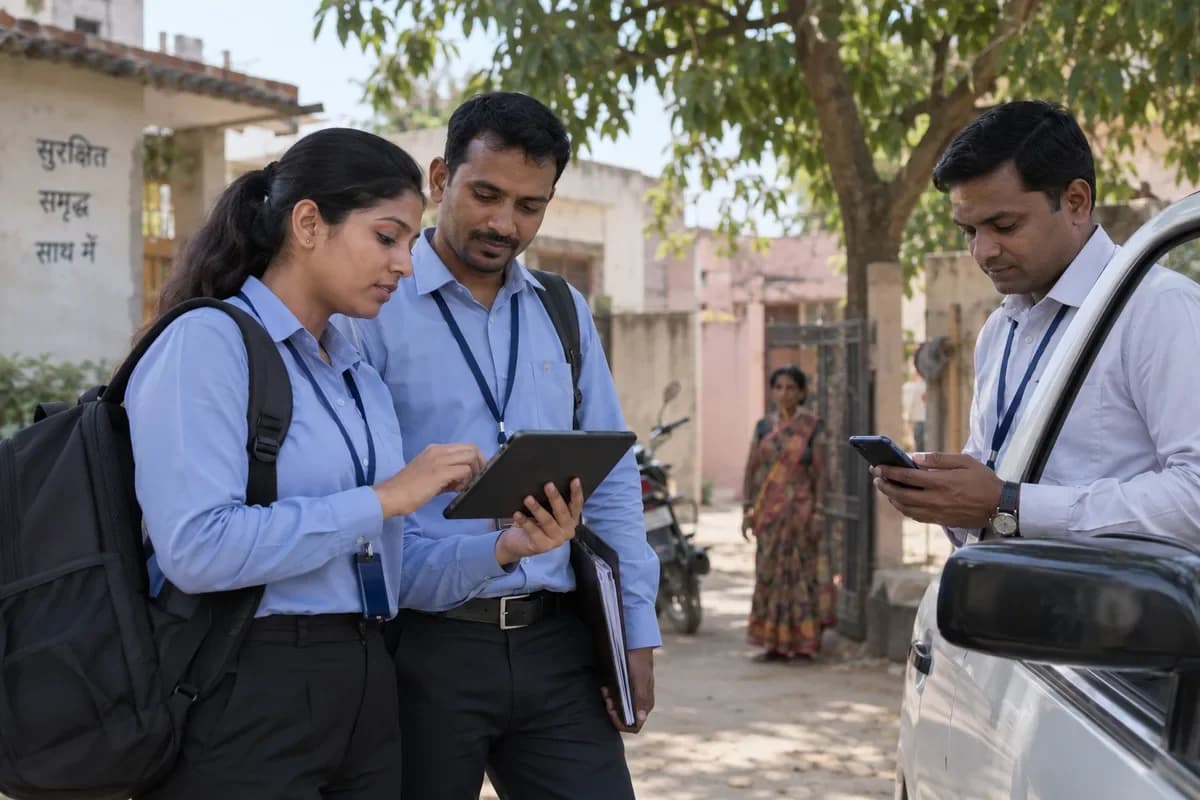
On the phone, in the street
The collection screens open in the phone’s browser. Nothing is installed, there is no store update to chase, and an older handset is enough. Each sign-in opens only that collector’s own route or groups.
What the route screen shows
Set up around how your field works
- Villages, centres, routes and SHGs configured from your own map
- Each collector given their borrowers and nobody else’s
- Entry rights without edit rights, so corrections pass through the office
- Receipts and reminders sent to the borrower by SMS or WhatsApp
- Collection against demand, by collector and by day, visible from the desk
What to ask about any field collection app
Vendors in this space stress offline capture, instant receipts and approvals before data reaches the loan record. Those are fair things to compare. This app saves an entry only when the phone has a connection, so it suits areas with some signal and needs a plan where there is none. Ask each vendor how sync works, what happens to an entry made without signal, and who can alter it afterwards.
Running a collection day well
A route is a plan, not a promise.
Safety and trust in the field
Collectors carry cash and handle sensitive conversations. The record protects both sides: the borrower has a receipt, and the collector has proof of what was taken. Agree a code of conduct for visits with your own team, because how a lender collects is as important as what it collects. The software records visits and amounts and does not govern behaviour.
A collector’s round, door by door
A collector’s day is spent walking between borrowers, with a phone in one hand. The app is judged by how it behaves at the door, not in the office. The phone is the tool.
Choices to settle before collectors carry phones
Giving collectors phones changes how the day is run. Several choices should be settled first. They decide what a collector can do in the field and what the office checks afterwards. Settle them before any route is loaded. Each choice is small.
Questions to settle before rollout.
Use a representative scenario to decide what this part of the system must show and where review is still needed.
The receipt at the door
Can the same receipt be allocated without counting the money twice?
Take an unallocated amount in “The receipt at the door” and apply it to the intended balance. Review the remaining amount and the original receipt reference together.
Background reading: ERPNext: payment allocation
Field Collection App for Loan Collectors
Does the schedule match the agreed terms and actual release of funds?
For “Field Collection App for Loan Collectors”, use a sample already checked by your finance team. Compare due dates and the principal and interest split before relying on the resulting balance.
Background reading: Frappe Lending: repayment schedules
Frequently asked questions
Is there an app to install from the Play Store?
No. The collector signs in through the phone browser, so a low-cost Android handset works and nobody is stranded on an old version.
What happens in villages with poor network?
An entry needs a connection to save. Collectors in thin coverage record receipts once they reach a signal or return to the centre, and the entry carries the time it was actually made.
Can a collector change a receipt later?
Only if you give that right. Recovery staff normally get entry rights alone, and an office user makes any correction, with the old and new amounts both kept in the log.
Can the office see collections live?
Yes. The receipt is stamped with its time when saved, so the desk reads the day against demand by collector.
Can a collector see other collectors’ borrowers?
No. Each sign-in opens only that collector’s own route or groups.
Does the app track the collector’s location?
The description does not claim location tracking. If you want it, raise it in scoping with your reasons, since it has privacy and staff-consent implications.
How are cash shortfalls handled?
Cash collected per collector is listed against receipts, so a shortfall carries a name, a route and a date. What follows is your policy.
How this feature fits the system.
Loan Management System: the parts that work with this feature, the trades that use it and the ways to put it in place.
Enquiries and leads
Each loan enquiry is logged with its source and a follow-up date, and reports show which enquiries turned into applications.
Lead ManagementSanction approvals
Approval levels are set by loan amount or product, disbursement waits for the required sign-off, and the log records who approved and when.
Workflow and ApprovalsCollection app for field agents
Field collectors record instalment receipts against the borrower from a phone browser, and due and received amounts appear together with collector name and date.
Receipts ManagementTell us what you need.
Tell us what your team does today, where work gets stuck and what you want to change.
What happens after you share your requirements
- We review your brief and the systems you already use.
- We clarify the workflow, missing information and the work to consider first.
- The proposed scope sets out the deliverables, responsibilities and dependencies.
- Review the scope and commercial terms before deciding whether to proceed.
Start with your requirements
Describe your current process, the people involved and the change you need. Start with the details you know; we can clarify the rest together.
Share your requirements