Give every loan file a stage, a date and an owner, and check every payout.
A loan agent, or direct selling agent, places files with many lenders over chat messages and a lead sheet, so files stall and payouts go unchecked. The software tracks enquiries, document checklists and sanctions, and it adds the payout ledger and the connector ledger that a loan agent depends on every month. Every file has an owner.
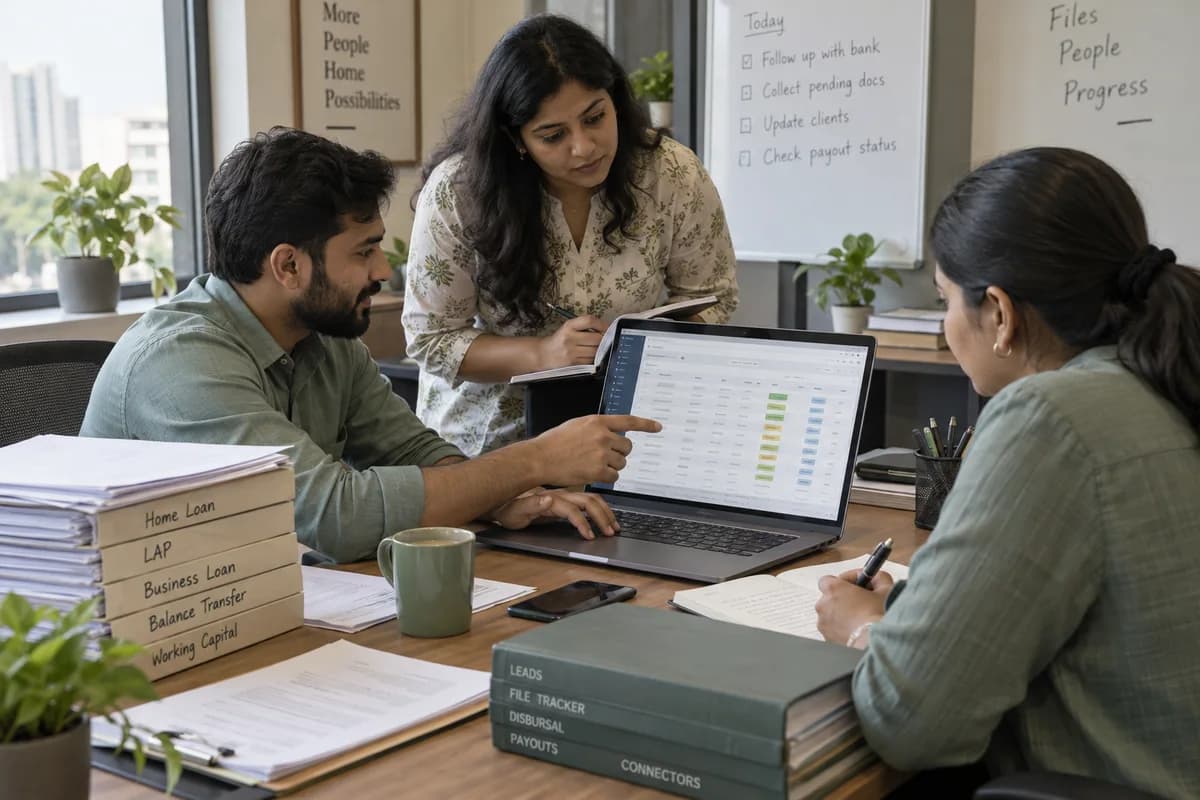
You source home loans, property loans, business loans and working capital limits, then place each file with the lender most likely to approve it.
Two things decide your year: files reaching disbursal, and lenders paying what they owe. Both come down to follow-up.
A lead comes from a builder, an accountant or a connector. You collect ID proofs, salary slips or income tax returns, bank statements, business tax returns and property papers, mostly as photos sent over chat. Then you pick the lender, log the file under your agent code, and wait for the bank to confirm that it has been opened.
After login the file moves through credit, personal discussion, legal and technical, sanction and disbursal, and every stage asks for one more document. The client calls you, not the bank, to ask where it has reached.
The payout on the disbursed amount follows months later, against your tax invoice. Part of it belongs to the connector or sub-agent who brought the case, and that person remembers the disbursal date well.
What goes wrong for loan agents and DSAs without a proper system.
What we would build for loan agents and DSAs.
Named the way your team already talks about the work. We start with whichever part the audit shows is costing you most.
A requirements checklist for loan agents and DSAs.
What to cover, which reports to ask for and what to put to every vendor, ready to print or save as a PDF.
A product already built for loan agents and DSAs.
It is adapted to how your business works before it goes live, and anything your trade needs that it lacks is added then.
Loan Management System
Enquiries, applications, sanction, disbursement, instalment schedules and field collections connected on one loan record.
Other products in the same sector as loan agents and DSAs.
- Bank Management Software
- Business Finance Provider Management Software
- Chit Fund Management Software
- CA Practice Management Software
- Credit Union Management Software
- General Insurance Agency Management Software
- Health Insurance Agency Management Software
- Insurance Broker Management Software
- Life Insurance Agency Management Software
- Loan Officer Management Software
- Bank Reconciliation Software
- Mutual Fund Distributor Management Software
- All industry products
The business modules loan agents and DSAs use most.
Each one is also available on its own, or inside a system built for you.
- Lead Management
- Workflow and Approvals
- Receipts Management
- Collections and Payment Follow-Up
- Audit Trail
- Commission and Incentives
- Document Management
- All business solutions
All solutions by area
- Applicant Tracking (5)
- CRM (8)
- Finance & Accounting (10)
- Helpdesk (4)
- Human Resources (13)
- Inventory Management (5)
- Project Management (7)
- Manufacturing (6)
- Procurement (4)
- Sales and Distribution (6)
- Field Service (5)
- Statutory and Compliance (4)
- Retail and POS (4)
- Bookings and Appointments (3)
- Subscriptions (2)
- Assets and Fleet (4)
- Platform (6)
- Analytics (2)
- Documents (1)
Where AI can help loan agents and DSAs.
Each one reads records you already keep, and a person approves every decision.
Tools loan agents and DSAs often connect.
The services behind it.
Business Process Automation
Approvals, reminders, follow-ups and reports that run on their own instead of on someone remembering.
Learn moreCustom Software and Product Engineering
Software built around how your business actually runs, when nothing off the shelf fits without workarounds.
Learn moreERP, CRM and Business Software Implementation
One record of stock, orders, customers and accounts, set up so your team opens it every day.
Learn moreData Protection and Privacy Readiness
Personal data hides in odd places. We map every CRM, billing export, enquiry inbox and backup that holds it, then build consent records, access roles, retention jobs and a breach runbook into the software. Your lawyer reads the privacy law.
Learn moreAll our other services
- Software Maintenance, Support and Rescue
- AI and Intelligent Automation
- API and System Integration
- Data Engineering and Business Intelligence
- UI/UX Design and Prototyping
- Cloud Engineering and Managed Infrastructure
- DevOps & Automation Services
- QA and Software Testing
- Performance Engineering
- Cybersecurity and Application Security
- IoT and Edge Computing
- Technology Strategy and Product Consulting
- E-Commerce and Digital Commerce
- MVP Product Development
- Web and Mobile Application Development
- SaaS Product Development
- WhatsApp Business API and Chatbots
- Data Migration and Moving Off Spreadsheets
- Training and Adoption
- Tax and e-Invoice Engineering
- Managed IT Support
- Dedicated Team and Staff Augmentation
- Business Intelligence and Reporting Tools
- Cloud Cost Optimisation
- Global Compliance and Localisation
Written for loan agents and DSAs.
Practical notes on running the business, not product marketing.
How the work runs from Bengaluru for your city.
- 1
The audit, by call
A screen-share and a look at the sheets, accounting reports and WhatsApp groups your team uses. No travel needed.
- 2
A written proposal
Scope, what we build first and the cost, agreed in writing before anything starts.
- 3
Build in short rounds
Working screens shared every few weeks. Your team tests them from your own office.
- 4
Go-live, in person when it helps
For data migration and training we can come to your city. Travel is agreed in advance.
- 5
Support online
Fixes, changes and hosting handled remotely by the same team that built it.
Software we have built and run in this sector.
Published with the client’s agreement, with what was built and what changed.
Questions loan agents and DSAs ask before they call.
Is a lender’s loan management system suitable for a loan agent?
Not straight out of the box. We rebuild the core around your file pipeline and your payouts rather than EMI collection, and drop the parts a DSA never opens.
Can it fetch a credit score or a bureau report?
No. Bureau access sits with the lender, and the software records what the credit team tells you. Repayment ratio and eligibility notes are entered by your executive.
Who can see customers’ bank statements and income tax returns?
Only the executive handling that file and the managers you name. Documents sit on the hosted system, and every change to a file carries a name and a date.
Should we just use the lender’s agent portal?
Use it for login and status with that lender. It will not show your files across all lenders, or what each of them still owes you.
What are the price factors for a DSA or loan agency?
How many executives, branches and connectors use it, the lenders whose checklists differ, and the parts selected: file register, stage tracker, payout invoicing or connector ledger. Messaging tools to link are counted. The quotation shows each part’s price.
What should a loan agency prepare for the first sessions?
Gather a current file list, the document checklist for each loan type, a lender payout sheet and the connector commission statement. A senior executive, an accounts person and a connector coordinator need to answer questions and look at screens. Name them early.
If we leave, who has the client files and commission records?
The agency does. Files, payouts and connector ledgers are your data, and the software is yours too. Ordinary spreadsheet exports are available. Support continues from its developers, with hosting at GullySystem unless you choose otherwise.
What happens after I share my requirements?
An engineer reads what you send and replies within one business day. We then look at the software, spreadsheets and WhatsApp groups your business runs on today and write down what works, what slows your team down and what is missing. A demo login, a screen-share or a few screenshots are enough. You get a short written summary ordered by priority, with no obligation to hire us afterwards.
How much will the software cost?
We don’t publish a price, because it depends on what the system has to do. That first review settles the scope, and the cost goes into a written proposal before any work starts.
Bengaluru areas with many loan agents and DSAs.
Cities where loan agents and DSAs are common.
Related industries.
- Banks
- Business finance providers
- Chit fund companies
- Company secretaries
- Credit unions
- General insurance agents
- Health insurance agents
- Insurance brokers
- Life insurance advisors
- Loan officers
- Microfinance institutions
- Mutual fund distributors
- Non-banking finance companies
- Payment service providers
- Private equity firms
- Stock brokers
- Wealth managers and financial advisers
Part of a wider group.
Tell us how your business runs today.
A few lines on your spreadsheets, software and WhatsApp groups is enough. We reply the same working day.
What happens after you share your requirements
- A senior engineer reads your answers. Nobody phones first.
- Within one business day you get a written note: what we understood, what we would start with, and the questions we still have.
- If it fits, a proposal follows with the order of work, what we need from you and what you receive at each step.
- No call is booked and nothing is paid until you have read the note. Your details stay with us.
Start with your requirements
Seven short steps that tell us what you need. A senior engineer reads them before anyone gets in touch.
Share your requirements