Role Views for Lenders and Loan Staff
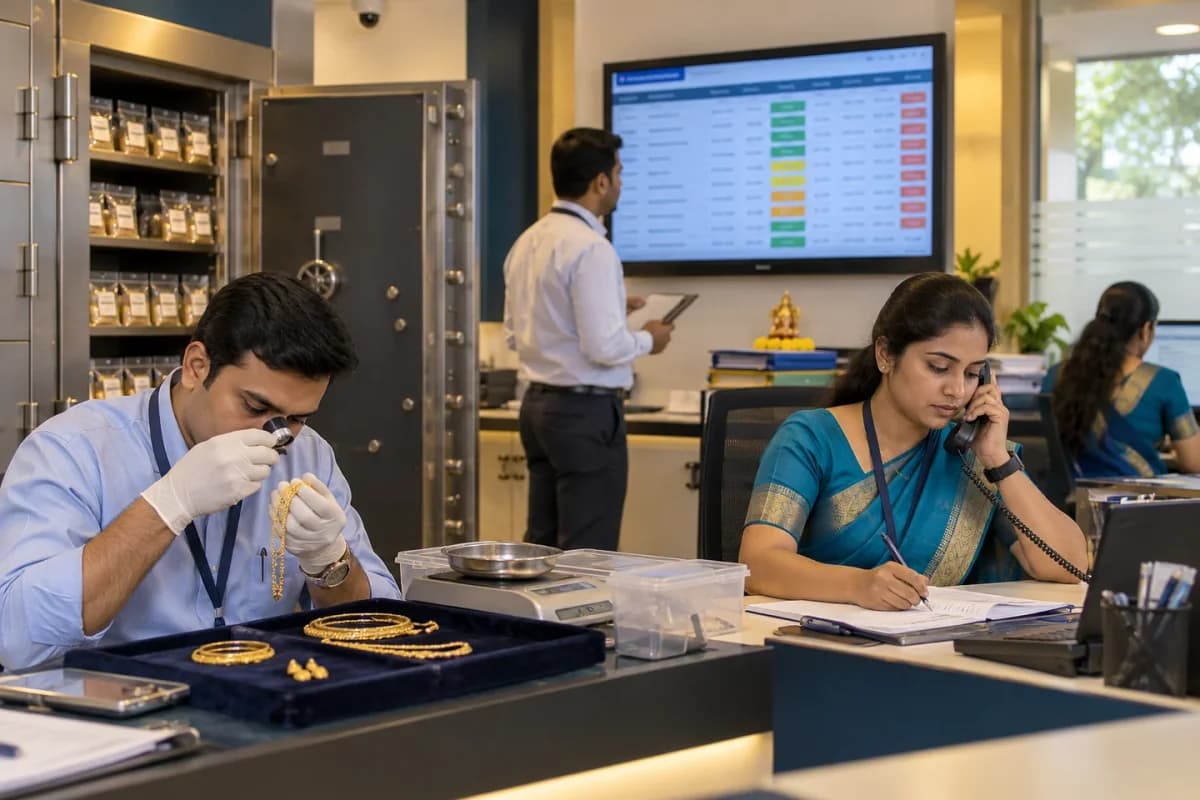
Owners, loan officers, field collectors and accountants work on the same loan records and see the part that concerns them. Borrowers can be given a narrower view of their own accounts.
Who uses it
The system is used by microfinance organisations and NGOs that lend to or through Self Help Groups. Co-operative credit societies use it for a record of members’ loans and deposits. Vehicle finance firms, chit funds and moneylenders with field staff use it for schedules and collections.
What each role sees
How access is set
Approval levels are set by amount or product, and disbursement waits for the sign-off that the level requires. A collector sees only the borrowers assigned. A branch head sees a branch. Each entry is stored under its author’s name.
What the lender decides
Which roles exist, what each may see and edit, and what a borrower may do on the portal are agreed with the lender before go-live. Routes, villages, centres and branches are entered at the same time.
What buyer checklists ask about roles
Lending software reviews return to access control again and again, because a loan record holds money and personal details.
Planning roles before the first login
A short exercise before go-live saves arguments later.
- List every person who will touch loan records and write the one job each does
- Decide who may approve which amount band
- Decide whether borrowers get a portal at all
- Name the person who adds and removes users
Four seats, one loan, a single day
Each seat shows a different slice. These four moments follow the same loan through the office, from the morning list to the evening ledger.
Choices that shape access before the first login
A lender who takes a short meeting before launch avoids a string of small corrections afterwards. These four decisions set the shape of every screen for every person in the team. Keep it brief.
Agree the evidence before signing off this part.
Use a representative scenario to decide what this part of the system must show and where review is still needed.
Loan officers
Does the schedule match the agreed terms and actual release of funds?
For “Loan officers”, use a sample already checked by your finance team. Compare due dates and the principal and interest split before relying on the resulting balance.
Background reading: Frappe Lending: repayment schedules
Scope by branch or route
Which observation would change the proposed scope?
For “Scope by branch or route”, observe someone completing the task with a representative example. Record where they stop, ask another person or re-enter information, then choose the smallest change whose result the team can verify.
Background reading: GOV.UK: researching user needs
Frequently asked questions
Can a collector see another collector’s borrowers?
No. Each collector sees only the route or groups assigned to them. Which borrowers sit with whom is set up with the lender.
Can an officer approve their own file?
Approval levels are set by amount or product, and the log shows who approved and when. Who holds each level is for the lender to decide.
Do borrowers need to log in?
Only where the lender offers the portal. Borrowers who keep paying the collector in cash can carry on, and that continues to work.
Can a branch head see only their own branch?
Yes. Access follows the role and the branch assigned, and the reports can be limited the same way.
Who adds a new user?
The lender names the person responsible, such as the owner or an administrator. Agree this at go-live so a new collector is not left sharing someone else’s login.
What happens to a collector’s borrowers when the collector leaves?
The borrowers are reassigned to another person and the login is closed. Entries the collector made stay on the record under the collector’s name.
Can an accountant see everything?
Only what the role is given. Most lenders let the accountant see collections, deposits and exports, and keep appraisal notes to the loan officers.
How this feature fits the system.
Loan Management System: the parts that work with this feature, the trades that use it and the ways to put it in place.
Enquiries and leads
Each loan enquiry is logged with its source and a follow-up date, and reports show which enquiries turned into applications.
Lead ManagementSanction approvals
Approval levels are set by loan amount or product, disbursement waits for the required sign-off, and the log records who approved and when.
Workflow and ApprovalsCollection app for field agents
Field collectors record instalment receipts against the borrower from a phone browser, and due and received amounts appear together with collector name and date.
Receipts ManagementTell us what you need.
Tell us what your team does today, where work gets stuck and what you want to change.
What happens after you share your requirements
- We review your brief and the systems you already use.
- We clarify the workflow, missing information and the work to consider first.
- The proposed scope sets out the deliverables, responsibilities and dependencies.
- Review the scope and commercial terms before deciding whether to proceed.
Start with your requirements
Describe your current process, the people involved and the change you need. Start with the details you know; we can clarify the rest together.
Share your requirements